Honeywell no longer owns its armor business. That sentence matters more than most people realize when talking about graphene-infused smart armor.
When Honeywell completed its three-way breakup in 2026, the advanced materials division that housed Spectra fiber, the high-performance ballistic material used in military helmets, vests, vehicle armor, and naval systems, went with it. That business now trades independently as Solstice Advanced Materials (NASDAQ: SOLS), spun off October 30, 2025. HON retained automation. HONA got aerospace. SOLS kept the armor supply chain.
The market has not caught up.
Why Graphene Changes This Calculus
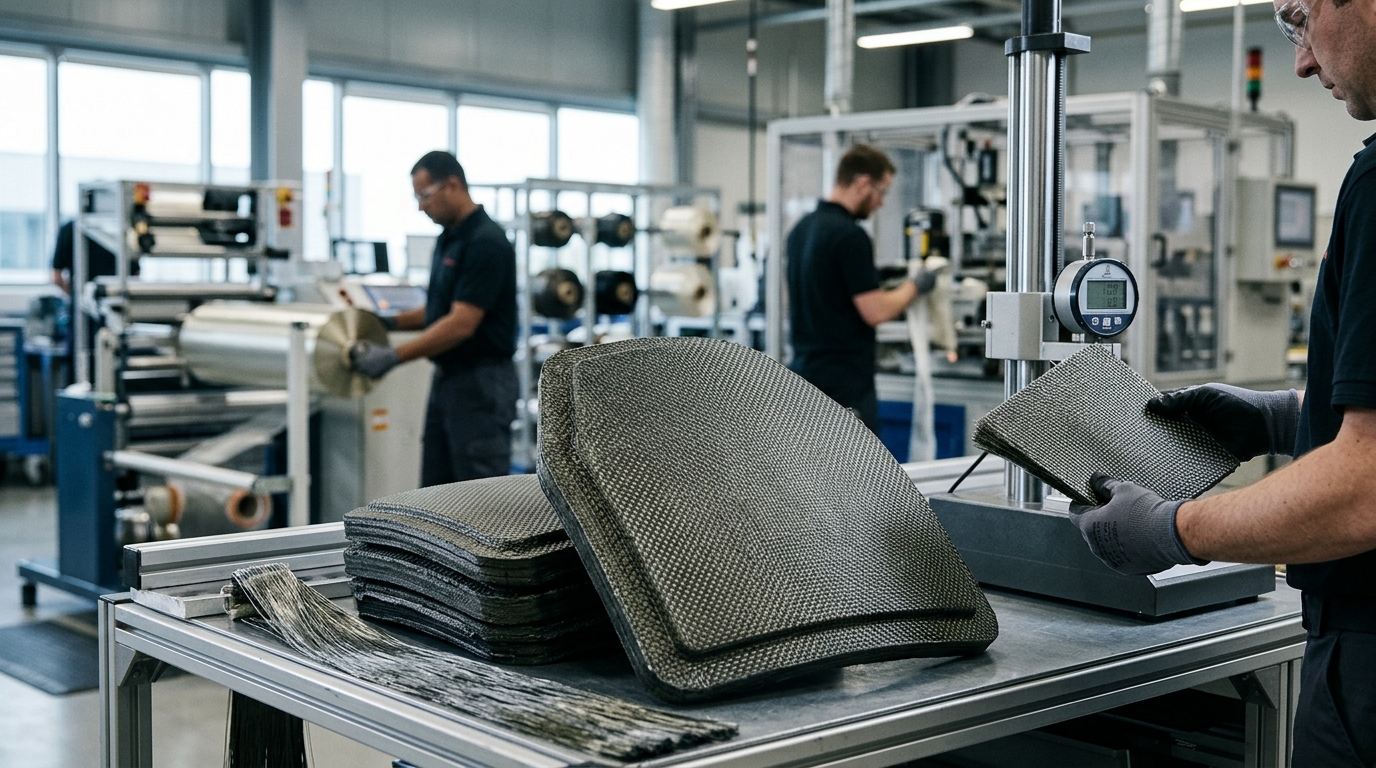
Traditional ballistic fibers like Spectra, built from ultra-high-molecular-weight polyethylene, are commonly described by the company as having a strength-to-weight advantage versus steel. Graphene composites push that further. Research published in 2026 has reported that graphene-based hybrid composites can improve ballistic limit velocity and reduce backface deformation versus conventional ballistic materials, with gains attributed to mechanisms including stress-wave effects and crack deflection. Claims of 35 to 45% weight reduction versus traditional armor vary by design and test standard, so treat them as directional rather than a guaranteed outcome.
The scalability problem, cost and agglomeration, has narrowed enough that commercial adoption is accelerating. SOLS is not waiting around. In January 2026, Solstice announced an investment of more than $220 million to expand its Colonial Heights, Virginia facility, upgrading fiber spinning, composite coating, and analytical capabilities. The company said the buildout is expected to create 100 new full-time jobs by 2029.
The Options Angle
SOLS closed at $60.38 on October 26, trading about 33% below its 52-week high of $90.80, with an average analyst price target of $79. That is a 31% gap between current price and the average target. IV30 has been running in the high 40s to low 50s in recent weeks, elevated for a mid-cap specialty materials name. The stock reports November 4, before the open.
Activist investor Starboard Value took a stake in October and publicly demanded about $100 million in cost cuts, as Reuters reported. That adds a near-term catalyst that defense supply chain momentum alone does not provide. When activists and a rising defense budget land on the same name in the same month as earnings, the options market tends to underprice the skew.
The structural tailwind behind SOLS extends well beyond a single activist campaign. A proposed $1.5 trillion FY2027 defense budget is reshaping procurement priorities across the entire supply chain, not just the primes.
A defined-risk bull call spread in the November or December expiry, structured around the earnings date, lets traders express a view on both the operational story and the Starboard-driven restructuring without open-ended downside. The wide bid-ask spread on near-term contracts warrants checking liquidity carefully before sizing.
What Would Break the Thesis
Graphene armor still faces production cost and scalability hurdles that could slow Defense Department procurement timelines. SOLS also carries a premium multiple, rich for a chemicals spinoff still eliminating stranded costs. A weak November 4 report, particularly on Protective Materials performance and any update on the Virginia facility ramp, would pressure the stock before any material order flow from the graphene transition arrives.
Procurement timelines for advanced materials face a second constraint beyond graphene scalability. A statutory ban on Chinese-origin rare earth materials in defense systems takes effect January 1, 2027, reshaping which suppliers can qualify for Pentagon contracts.
Monitor the segment revenue line and any guidance language around the Virginia facility ramp. That is where the graphene story moves from R&D to revenue.