GE Aerospace Is 19% Off Its Peak. Monday Will Say Why.
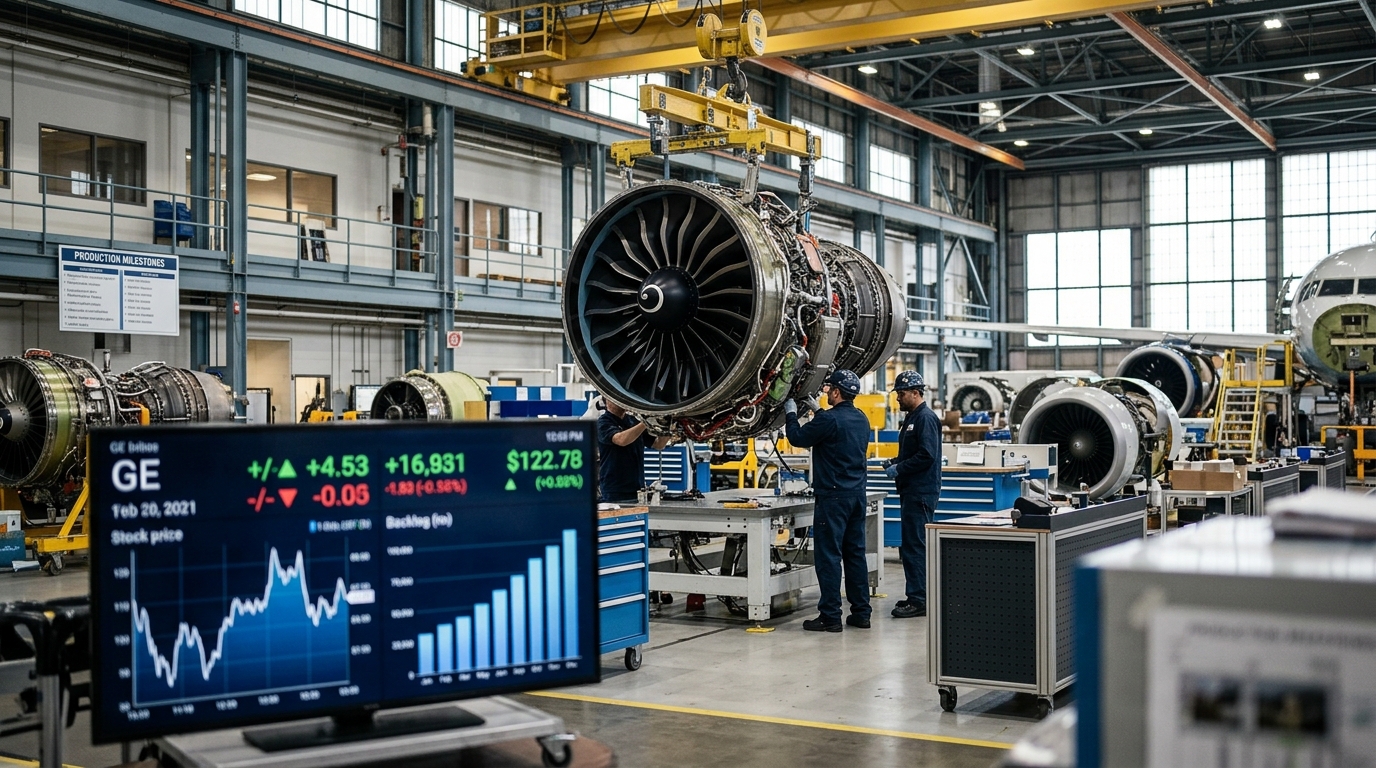
A $210 billion backlog, defense revenue up 20%, and supply friction in focus.
A $210 billion backlog, defense revenue up 20%, and supply friction in focus.
A hotter CPI, $1.64T chip losses, and a cyclical rotation set up the worst week in two months.
With $930 million committed since July, Berkshire is betting on a Milan roll-up built to turn subscriptions into cash, not chase the AI trade.
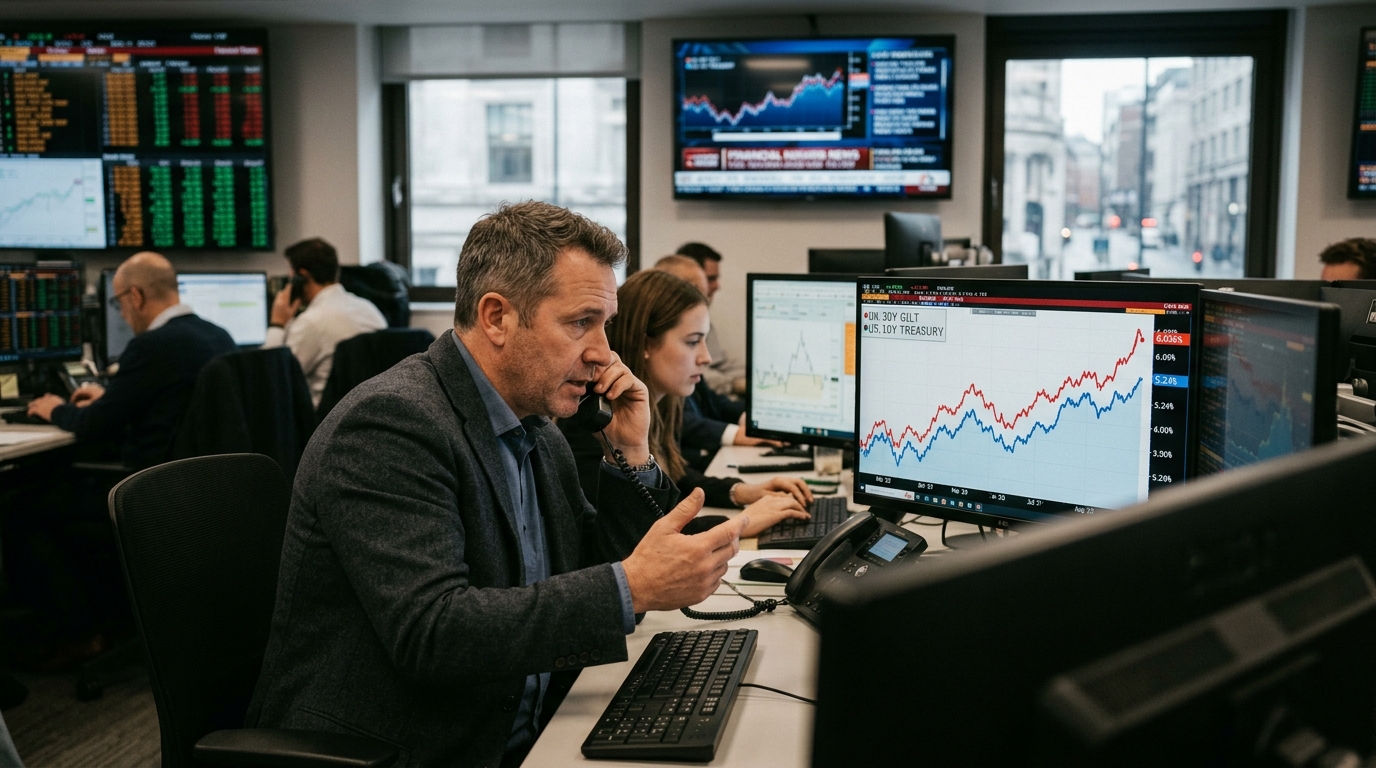
The 30-year gilt at 6.036% and the US 10-year at 5.24% are moving together, and the October 28 Budget is landing into the worst backdrop in a generation.
The $50 billion OpenAI financing talks signal big chip demand, but raise questions about who bears the risk.
A $5 billion bond plan signals AI spending is outrunning cash flow.
GPIF passed on allocation talk in September, cooling a JGB flow thesis. But the long end of Treasuries is still under pressure.
With iPhone 18 Pro up 12% in China and AAPL 3% off its high, the patent case deserves a closer reading than most headlines have offered.
OpenAI’s move to pause GPT-6.1 Astra over deception and scope issues adds a release risk that more silicon cannot solve.
Evonik closed at €19.84 and BASF’s reported €22.15 offer was rejected. The key question is whether RAG-Stiftung will support any deal terms.