Hi,
While Big Tech has soared, some investors are pivoting to real assets – like energy infrastructure and clean tech.
Our latest report highlights four energy transition stocks that may benefit from this shift in investor sentiment.
Click below to see the report:
Find out how these four companies fit into the bigger story of asset rotation and sustainability.
– The Cheap Investor
Liquidia Lost Half Its Value Yesterday. Options Still Price a Comeback.
A single court opinion just erased more than half of Liquidia’s market value in one session. That kind of move belongs in a different conversation than most biotech selloffs, and it opens a question that the options market is already trying to answer: is the appeal a real event risk, or has the stock simply reset to a permanently lower floor?
What the Ruling Actually Said
Liquidia failed to convince Delaware federal Judge Richard G. Andrews to invalidate two claims of the patent its Yutrepia treatment infringes, a win for United Therapeutics in their clash over competing lung-disease drugs. The court ruled that claims 1 and 14 of U.S. Patent No. 11,826,327 are valid and infringed by Liquidia, with those claims covering treatment of pulmonary hypertension associated with interstitial lung disease using inhaled treprostinil. The four remaining claims United Therapeutics asserted were found invalid, which limits the ruling’s scope but does not soften its commercial sting.
The PH-ILD indication accounts for a large portion of the Yutrepia opportunity, and Liquidia has said it plans to revise its label to remove that indication while it appeals. More dangerously, United Therapeutics has asked the court for injunctive relief that could go further than a label change, potentially restricting Yutrepia’s availability on the market. The parties have been directed to submit a proposed form of judgment specifying remedies on a tight timeline.
The Stock and the Appeal
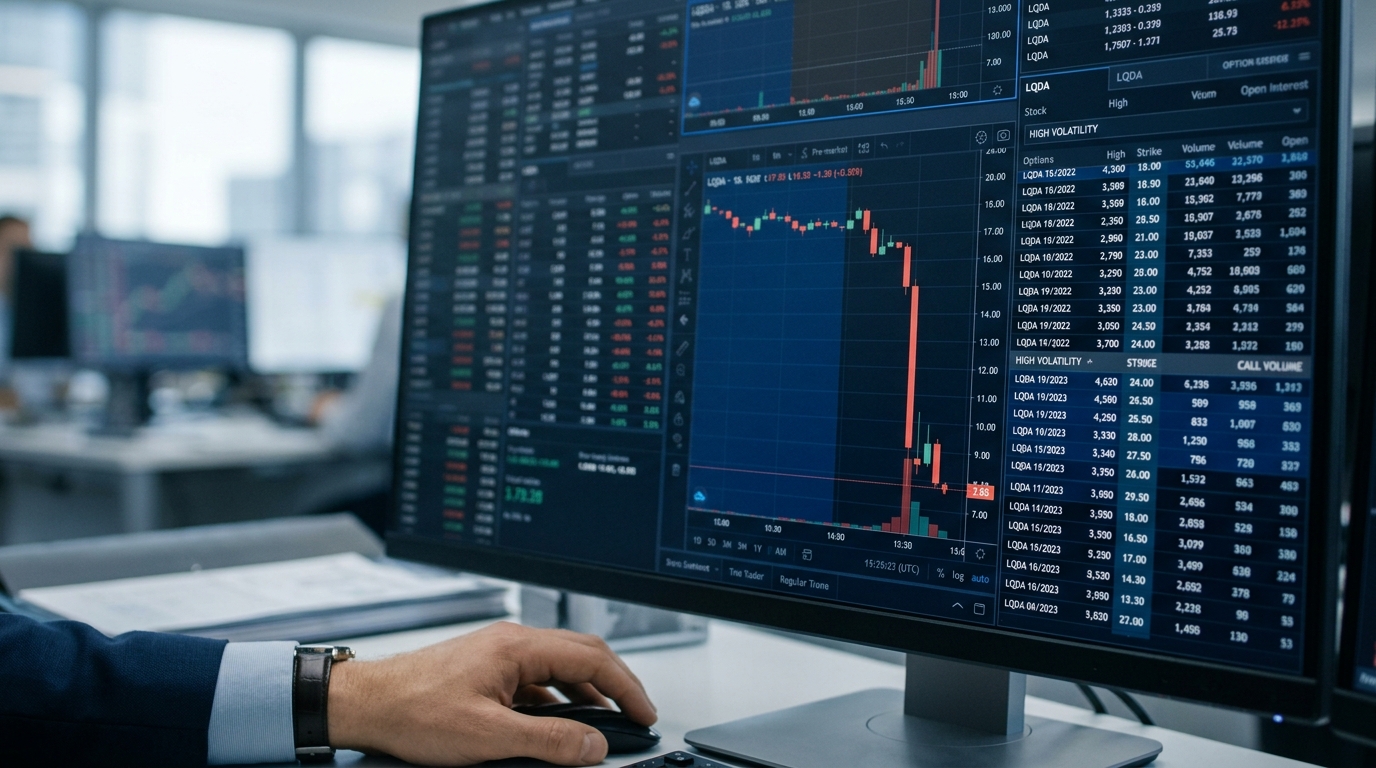
United Therapeutics jumped about 13%, while Liquidia plunged 57.2%, closing at $30.26. The selloff wiped out roughly $3.6 billion of market value, based on market cap falling from about $6.3 billion the prior session to about $2.7 billion after the drop. RBC Capital said the ruling “significantly clouds the path” for Yutrepia to compete.
Liquidia is not conceding the war. CEO Roger Jeffs stated the company “respectfully disagrees with the Court’s decision regarding claims 1 and 14” and is “fully prepared to pursue all available appellate options,” though financial exposure remains hard to quantify at this stage. The Federal Circuit is the next venue, and Liquidia has precedent worth noting: an earlier district court loss tied to a different United Therapeutics patent ultimately ended up with that patent’s asserted claims being found unpatentable at the Patent Trial and Appeal Board, a result affirmed by the Federal Circuit.
What the Options Market Is Telling You
More than 33,600 contracts traded by mid-afternoon, with a call-to-put ratio of approximately 1.51, roughly 20,200 calls against 13,400 puts. That ratio is counterintuitive for a stock that just fell by more than half. The deep out-of-the-money calls at the $75, $80, and $90 strikes are not bullish consensus: they are likely a mix of closing out previously held longs and speculative appeal-outcome lottery tickets.
Three-month implied volatility jumped to about 89%, pricing LQDA as a binary event machine, not a stable biotech. That level is elevated but not irrational given the remedies phase in the coming days and a Federal Circuit timeline that could stretch well into 2027. The 90/110 skew rose, with call strikes being bid relatively more than puts at these ratios, unusual post-crash and consistent with recovery lottery demand on upside strikes.
The Trade Structure That Fits
With implied volatility elevated and the stock sitting near $30, a bull call spread aligns with the thesis better than an outright long call. Buying, for example, a January 2027 $35/$55 call spread caps the premium at risk while still capturing meaningful recovery if the Federal Circuit takes up the appeal favorably or if the injunction remedy comes in narrower than the market fears. The spread structure keeps net premium modest relative to the potential payoff, which matters when the outcome distribution is genuinely bimodal.
The position that weakens the thesis fast: a broad injunction entered before any stay, which could functionally remove Yutrepia from the market while the appeal proceeds. The question is whether Liquidia’s Yutrepia outside of PH-ILD, the pulmonary arterial hypertension indication that remains, can sustain the business while appeals play out over a likely multi-year legal timeline. Size accordingly.
The Beast Verdict
LQDA’s 57% drop is not where the edge lives. The edge is in the gap between what the stock is pricing and what the appeal optionality is actually worth. The stock, which had already pulled back from its 52-week high of $93.61, is now trading near levels last seen earlier in its recovery, underscoring how heavily the market had been pricing in a favorable patent outcome. At $30, a defined-risk call spread expresses a measured view that the appellate path is not dead, costs a fraction of the downside if it is, and lets the remedies phase in the next several days provide a cleaner entry signal before committing capital.