Dear Investor,
The Trump memecoin is running another contest.
Hold enough of it by November 12th and you could land a seat at a dinner with the President on November 22nd.
Here’s the catch…
Just to be near the cutoff, holders were sitting on roughly $119,000 worth of the coin. And that’s for a dinner where, by the contest’s own rules, there’s no private meet-and-greet.
Meanwhile, the token itself trades about 97% below its peak.
Look, I’m a big believer in what this administration has done for crypto. But a dinner invitation isn’t an investment thesis.
If I had six figures to put into crypto this fall, I wouldn’t be chasing a leaderboard.
I’d want a coin with real users, real activity, and a real reason to grow that doesn’t depend on a contest.
That’s exactly what my #1 pick has. It’s a project people actually use every day, still priced well below where I believe it’s headed…
No dinner and no gold watch.
Just a setup I believe could pay far more than either.
My full report is normally $97. Today, $3.
Full Report: Get my #1 coin instead of Trump’s memecoin
To your massive success,
Bryce Paul
Crypto 101
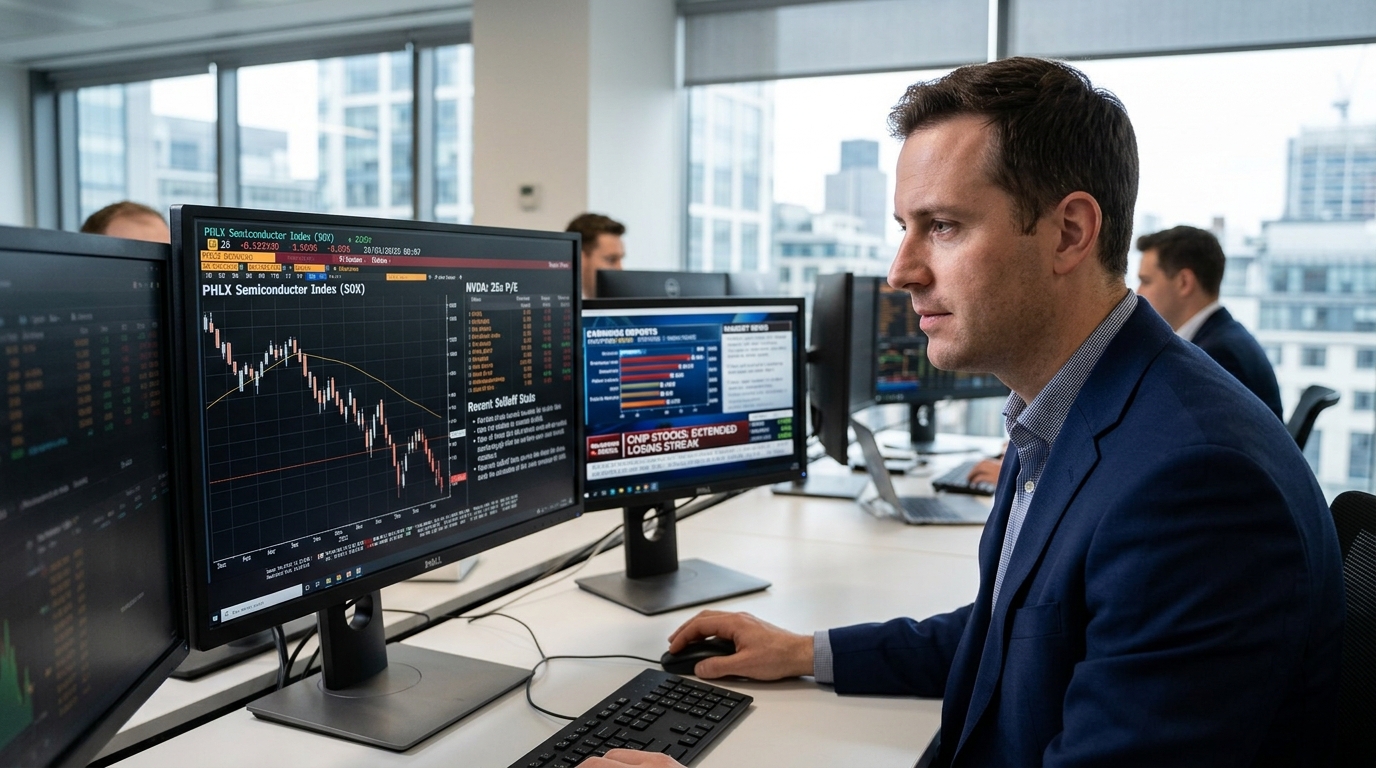
Nvidia at 25x Earnings After Eight Days of Chip Selloff
Eight sessions. Twelve percent gone. Contrarian traders have amassed an estimated $32 billion in gross paper gains over the last seven days, according to S3 Partners data compiled by Bloomberg, as the Philadelphia Semiconductor Index sank more than 12% and extended those losses to an eighth straight session on Friday. That streak matches the longest the SOX has endured since 2006. The index closed below its 50-day moving average, and the Nasdaq Composite shed 2.14% Friday to close at 26,140.03. For the week, the Nasdaq fell 4.5%, snapping a monthlong winning streak with its worst week since late June.
The breadth of the damage is hard to minimize. Twenty of the SOX’s 30 components have slid by more than 10% since the rout started. Coherent dropped close to 30%. Astera Labs, Macom Technology Solutions, and Credo Technology Group each lost over 20% in the eight-day slide. But the destruction in the smaller names should not obscure the more important question for options traders: what are the large-cap AI names actually worth at current prices?
The Valuation Picture Has Changed
Here is what the selloff has done to multiples. Nvidia’s forward price-to-earnings ratio sits at roughly 25x. AMD had rallied 184% year to date through August and was trading near 40x forward earnings; Nvidia, after a more modest gain of 23%, trades closer to 25x. Micron, still digesting its HBM ramp, is among the cheapest, carrying a trailing P/E of roughly 12x.
These are not the valuations of a sector priced for perfection. The bull case rests on earnings delivery. Nvidia’s earnings are expected to grow roughly 70% next year. Nvidia has not confirmed its next earnings date, but Wall Street widely expects the report around late November, with a consensus EPS forecast around $2.47 against last year’s $1.30. AMD reports first, with its fiscal third-quarter results confirmed for November 3. Both prints land while the memory of this week’s rout is still fresh.
The bear case is more nuanced than simple multiple compression. Broadcom CEO Hock Tan said at a Singapore event this week that many AI investors resemble casino gamblers, arguing they lack a clear understanding of the technology they are funding. More pointed was his assessment of constraints. Tan said financing could become a bigger obstacle than chips, memory, or electricity, calling capital access the industry’s potential biggest constraint. This from the CEO of a company whose Q3 AI semiconductor revenue grew 221% year over year to $16.7 billion. When the biggest beneficiary of the buildout questions the funding model, traders should pay attention.
The Options Opportunity
The asymmetric trade here is a bull call spread on Nvidia into late November. The thesis is straightforward: the selloff has pulled Nvidia to multiples that discount a growth deceleration that has not yet appeared in the numbers. NVDA beat EPS estimates by 6% or more in each of its last four reports. The next report will be the first scorecard for Blackwell volumes at scale.
A November 21 expiry bull call spread, buying a call at or near the current market price around $214 and selling a higher strike roughly 10-15% above, keeps premium outlay defined while capturing a meaningful portion of any earnings-driven recovery. The position expires before the report, capturing the IV expansion as the event approaches rather than the binary risk of holding through it. Traders who prefer to hold through the report can roll to a post-earnings expiry or size down for the event.
What Would Break the Thesis
The index remains under pressure from concerns over AI spending, rising interest-rate expectations, and intensifying competition in the memory-chip market. Any guidance cut from AMD on November 3 would reset expectations across the complex before Nvidia reports. Investors have also grown concerned that tech companies are borrowing too much for the AI buildout. If financing stress spreads from neoclouds to the hyperscalers writing the chip orders, that would undercut the demand that Nvidia’s forward estimates assume.
The selloff has handed options traders a cleaner entry than anything available three weeks ago. At roughly 25x forward earnings with a November earnings catalyst approaching, Nvidia’s risk-to-reward has improved materially. The bears have had their week. The next move belongs to the earnings.