Dear Reader,
He finally came clean…
Legendary tech visionary and former Fox Business Host Matt McCall famously predicted over 50 stocks that went to soar to peak gains of 1,000%+ over the last 20 years…
Now, he’s out with his latest prediction…
It all ties back to what could be the biggest IPO in history…
And most importantly: why it could be a TRAP for investors like you.
Matt has a history of warnings like this.
Before Meta’s over-hyped IPO in May 2012, he warned viewers on CNN to wait about 2-weeks AFTER it’s IPO.
What happened next?
2 weeks after its IPO, Meta fell 20%…
Giving Matt’s followers an opportunity to get in at just $30 bucks.
Anyone who listened and held on through today could have seen gains as high as 2,497%.
And now McCall believes it could happen again.
While many mainstream pundits are hyping up this IPO…
His bombshell report just published could soon rock the markets.
Giving smart investors an opportunity an even better way to cash-in.
See his warning before Millions of investors make a big mistake >>>
Yours in smart speculation,
Stephen Prior, Publisher
Monument Traders Alliance
SAP Reports Wednesday. One Number Decides If AI Paid Off.
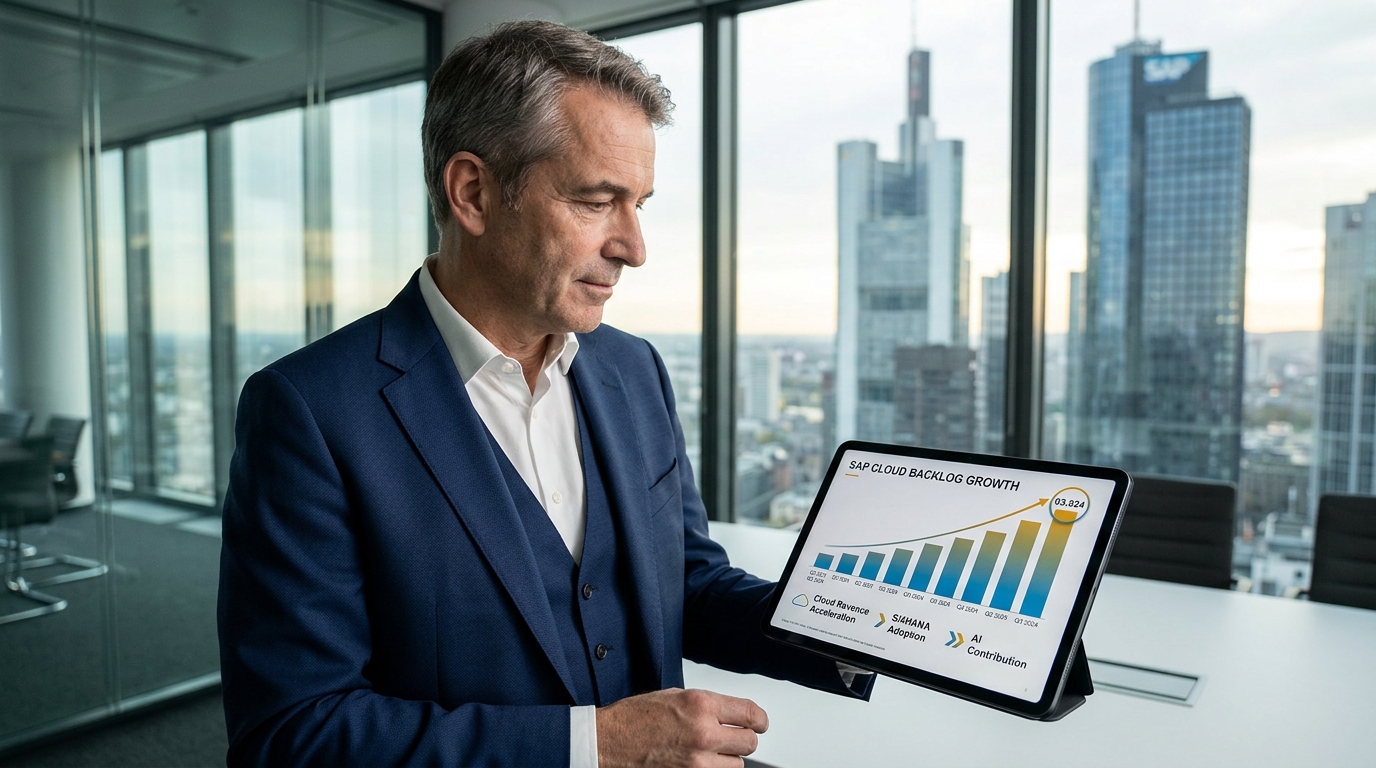
SAP missed on earnings last quarter. Then it spent the past two weeks announcing Joule Work, SAP Pay, and a TechWolf acquisition. Wednesday’s Q3 report, due after the U.S. market close on October 21, is the first hard test of whether any of that momentum is showing up in contracted revenue, or whether it is still a product roadmap looking for proof.
Why This Trade Stands Out
The market’s tolerance for AI investment stories without accompanying cash conversion has narrowed considerably in recent weeks. SAP’s options market is already pricing a move of roughly 7.5% in either direction around the report, according to analysis published by Saxo. That kind of elevated implied move, alongside an IV rank that climbed sharply in a single week to reach 70.8 as of October 9, tells you the options market considers this a genuinely binary event. A defined-risk position into that is precisely the kind of trade Option Beast is built for.
The Story Behind the Trade
SAP is expected to report Q3 2026 results after the market closes on Wednesday, October 21, with analysts forecasting earnings of $2.04 per share and revenue of $11.45 billion. That bar matters more than usual because SAP reported EPS of about $1.82 in Q2 versus a $2.00 consensus estimate, a miss of roughly 9%. Revenue came in at $11.27 billion versus analyst estimates of $11.30 billion.
What kept the stock from collapsing after that Q2 report was the cloud backlog. Cloud revenue rose 24% at constant currencies to €6.28 billion, and the current cloud backlog jumped 27% year over year, or 26% at constant currencies, to €22.9 billion. Shares dipped in regular trading after the Q2 release, then rebounded as investors digested the backlog strength and SAP said its 2026 operating profit outlook change reflected acquisition impacts rather than core demand.
Since then, SAP has kept busy. The company began the customer rollout of Joule Work at SAP Connect on October 6, with general availability for new assistants and agents starting in October. Joule Work is already live with 110,000 SAP employees, and SAP reports productivity gains of over 20% across finance, HR, and procurement from that internal deployment. SAP also launched SAP Pay, a payment service embedded in SAP Cloud ERP applications, provided by Tereina, an SAP entity dedicated to providing payment services. And SAP agreed to acquire TechWolf, an AI work intelligence platform, with the deal expected to bring TechWolf’s context graph along with its AI models and research team into SAP. The transaction is expected to close in Q4 2026, subject to regulatory approval.
Technical and Fundamental Alignment
SAP’s ADR was around $220 in mid-October. The current cloud backlog is widely regarded as a key gauge of future cloud revenue and customers’ willingness to commit to long-term arrangements. A Q3 read that sustains something close to the 26% constant-currency growth rate Q2 delivered would help validate the rebound. A clear deceleration could unwind it.
Competitors Oracle (ORCL), Salesforce (CRM), and Workday (WDAY) have all faced the same market question this cycle: how much of the AI product investment is converting to signed contracts? SAP’s October 21 report is the next data point in that industry-wide reckoning.
Options Perspective
SAP’s IV rank reached 70.8 and its IV percentile sat at 88.5 as of October 9, reflecting the earnings premium building in the front month. The options market is pointing to a move of about 7.5% in either direction, almost twice the stock’s usual reaction. With implied volatility elevated relative to recent history, a bull call spread expiring October 24 keeps the debit and the risk defined while allowing meaningful participation in an upside move if cloud backlog growth holds or accelerates. Buying the at-the-money call and selling an out-of-the-money call roughly 7% higher captures the directional thesis without paying for tail risk that may not materialize.
Time decay is not working against a buyer here given the three-day window to expiry. The risk is IV crush post-report compressing any unrealized gain, which is why the spread structure, rather than a naked long call, is the right form.
Risk Management
The thesis fails cleanly on two conditions. First: cloud backlog growth decelerates materially below Q2’s 26% constant-currency rate, signaling that AI product launches are not yet translating into signed orders. Second: operating profit guidance gets reduced again, reviving concerns about the cost structure of the AI buildout independent of acquisition impacts.
Several Joule capabilities are still waiting on their rollout dates. SAP has set multiple calendar anchors for its AI portfolio without any of them amounting to a completed deployment, a fact the market will weigh if the headline numbers disappoint. Position size matters. The premium paid on the spread is the maximum loss.
The Beast Verdict
SAP carries every element the Beast framework looks for: a clear catalyst, a specific metric the market is watching, elevated but not extreme implied volatility, and a stock that has already demonstrated it will move sharply in either direction on earnings day. For all the noise around pool dissolutions, buyback ledgers, and AI announcements, the decisive metric remains the cloud backlog, because it would show whether confidence about future cloud business is reflected in signed orders. Wednesday either validates the rebound from the mid-year low or reopens the question of whether SAP’s AI investment is ahead of its monetization. A bull call spread with defined risk expiring October 24 is the disciplined way to hold that view into the number.