The Shocking Truth about the AI Bubble
In just 48 hours, a tidal wave of bad news battered AI stocks:
- Chip giant Intel dropped 29%…
- Google had its worst day ever, losing $500 billion in value…
- And tech stocks plummeted by more than $1 trillion in one trading day…
That’s more than $153 billion vaporized each hour!
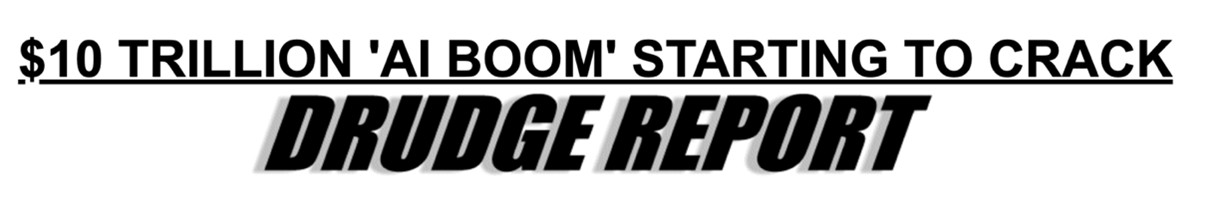
Top internet news site Drudge Report had this headline screaming at the top of the page…
“$10 trillion ‘AI Boom” starting to crack…”
So is the AI bubble finally bursting?
It sure as heck looks like it…
But here’s the shocking truth: it isn’t bursting for every stock.
On the same day Intel plunged 29%, the S&P 500 fell just 1.8%.
In other words, the stock market is splitting in two.
And the independent millionaire who recommended NVDA at $6 saw this coming.
He calls this stock market split the Great AI Shock.
On one side, the most hyped AI stocks could see a 77% meltdown…
On the other side, a little-known corner of AI that NVDA’s CEO calls a “once-in-a-generation opportunity” could produce triple digit gains over the coming months…
And the recent carnage is only the beginning – because the stock market split is just getting started…
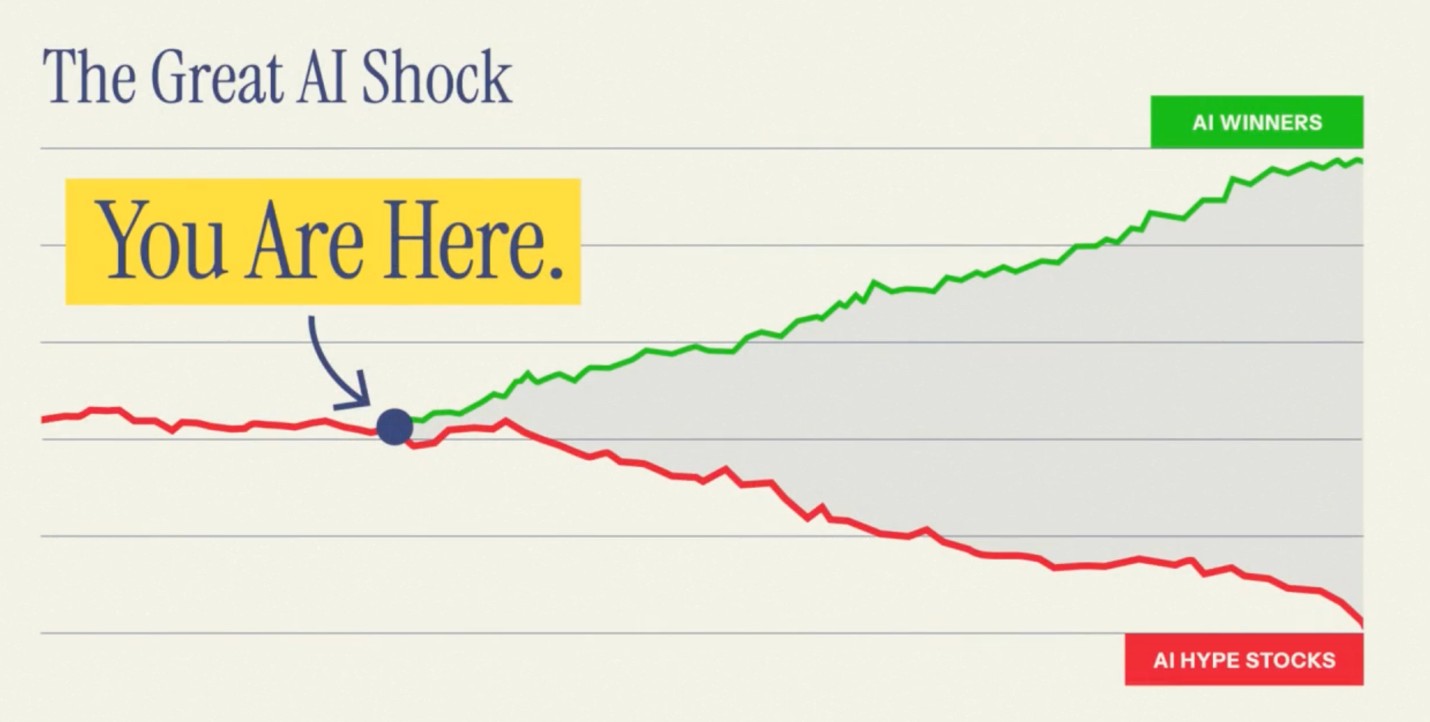
If you own any AI stocks, you need to decide which side of the split you’re on…
And you need to decide soon.
See the full story here, including details on the #1 stock on the right side of the split.
EXTR Is Up 15%. What a Buyer Actually Pays.
The Reuters report landed November 6, 2026. Extreme Networks is exploring a sale after attracting inbound acquisition interest, and the company is working with an investment bank on a formal process, according to people familiar with the matter. The stock moved accordingly: EXTR jumped roughly 15% that Friday. Four days later, traders are still wrestling with the same problem: how much further can this go if a deal actually closes?
That question is easier to frame with real numbers. The company’s market cap was about $3 billion at the time of the Reuters report. At $24.03 after the initial surge, the most widely followed valuation model for EXTR puts fair value at $33.50, implying the stock remains roughly 28% below that estimate even after the pop. Wall Street’s sell-side view is consistent: the consensus among analysts is a Moderate Buy with an average price target around $33 to $34. Neither figure incorporates a true control premium.
The names cited as potential acquirers include Fortinet, Cisco Systems, and NetApp, though none has been confirmed as a bidder and there is no certainty a transaction will materialize. Each brings a different strategic rationale. Cisco, Fortinet, and NetApp are each looking to expand their technology offerings and strengthen recurring revenue. For Cisco especially, Extreme’s CEO has said the company is winning business at the expense of incumbents, including Cisco, making the acquisition as much about plugging an attrition leak as it is about adding a platform.
The underlying business supports a premium argument. Total revenue in the most recent quarter reached $341.1 million, representing 10% year-over-year growth and continuing a streak of seven consecutive quarters with double-digit expansion. SaaS ARR reached approximately $265 million, up 22% year-over-year. Adjusted EBITDA grew 47% year-over-year, fueling 50% non-GAAP EPS growth. Platform ONE now accounts for over half of subscription bookings, with management expecting more than 50% of customers to be on the platform by the end of fiscal 2027. These are not metrics that struggle to attract a bid; they are metrics that invite a bidding war.
Sector context matters here. The move comes as networking consolidation accelerates, following Hewlett Packard Enterprise’s roughly $14 billion acquisition of Juniper Networks, which closed in 2025. IDC’s second-quarter 2026 Ethernet switch tracker put worldwide Ethernet switch revenue at $18.9 billion, up 43.4% year-over-year. The demand environment that attracted buyers to Juniper has not cooled.
The same demand wave is lifting adjacent infrastructure names. Optical networking revenue growing 40% year over year shows how broadly the AI buildout is pulling capital into network infrastructure.
The options angle centers on where EXTR trades relative to plausible deal outcomes. At roughly $24, the stock prices in the announcement but not the close. A transaction at $33.50 implies roughly 39% additional upside from current levels. A deal at a typical software acquisition multiple, applied to $265 million in SaaS ARR growing at 22%, could push considerably higher. A January call spread, buying the $26 strike and selling the $32, captures that corridor with defined and limited cost. Time decay works against you, but the catalyst timeline is not vague: a process with an investment bank and named suitors typically resolves within two to four months.
The thesis breaks if the sale process stalls, if no buyer meets management’s price expectations, or if the broader market for enterprise networking assets softens abruptly. Position size accordingly. Discussions remain at a preliminary stage and no acquisition agreement has been announced. That is both the risk and the reason the premium is still available.