Hi,
Take a look at this…
It’s smaller than a fingertip…
It’s made of glass…
And it’s about to unlock the next wave of AI growth.
Jensen Huang, Nvidia’s CEO, says this “light-speed” device is shattering the limitations of AI… and without it, AI can’t scale.
Google Ventures says it’s the future of AI compute…
And Sequoia Capital – the firm that backed Anthropic and OpenAI – calls it a “holy grail.”
Already, Elon Musk, Mark Zuckerberg, Cathie Wood, and Bill Gates are moving money to prepare for what’s coming…
Yet most Americans have never heard of it.
Wall Street insider Jason Bodner – the same man who called Nvidia at $4.50 – says this device is about to launch a whole new wave of AI winners…
And to prove it, he’s giving away his #1 stock involved with it – for free.
Click here to learn more. (No purchase necessary.)
We have so much to look forward to,
Jeff Brown
Founder & CEO, Brownstone Research
P.S. Stocks tied to this “light-speed” device already surged 133%, 217%, and even 320% – in a few short months. But it’s just getting started. Click here before the mainstream catches on.
Five Costco EVPs Filed Form 4s Before the Beat. Now What?
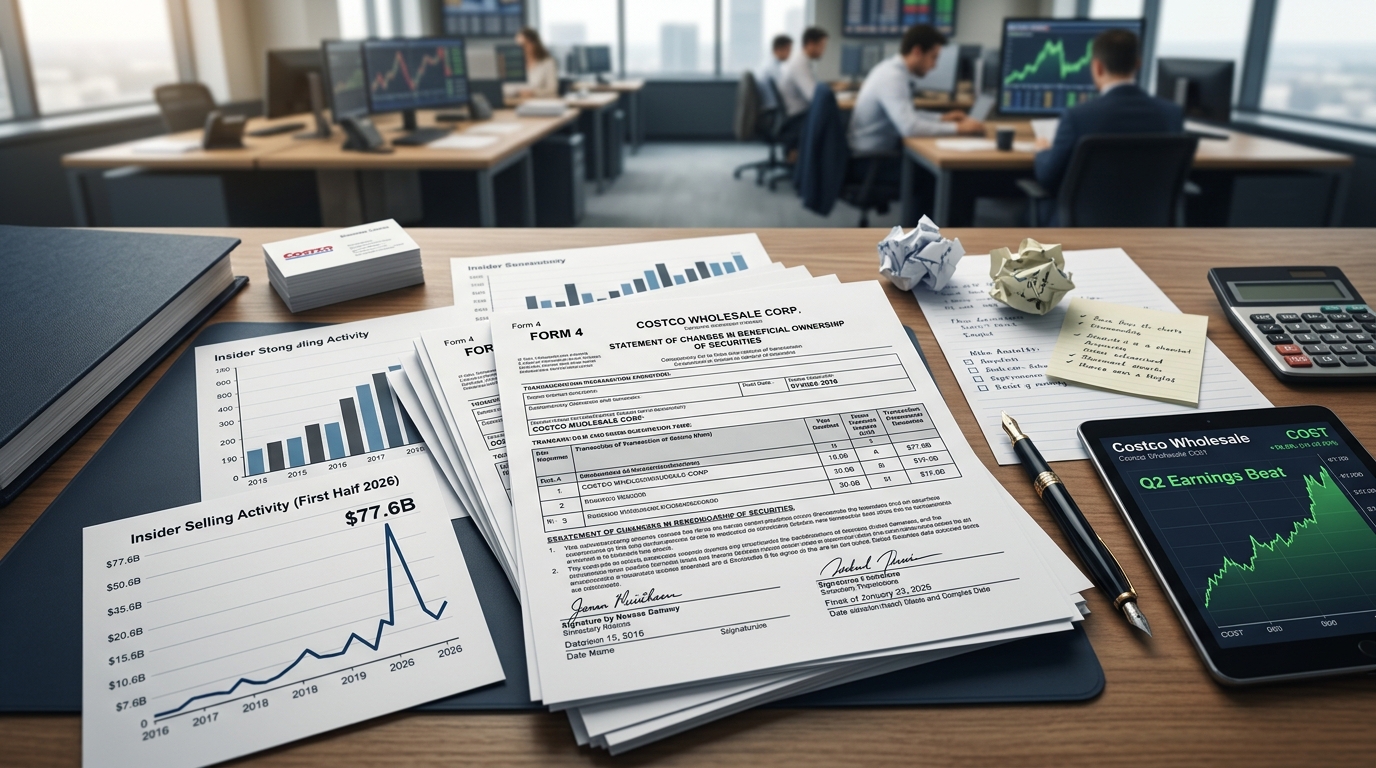
The contrast is stark. $77.6 billion. That is how much corporate insiders sold in the first half of 2026, a 20% increase from a year ago, according to EPFR Global Market Intelligence. The only period more intense in recent decades was 2021, when markets were flush with pandemic-driven stimulus cash. Against that backdrop, five Costco executive vice presidents filed Form 4s tied to equity awards dated September 10, fifteen days before the company’s fiscal Q4 report.
That cluster filing is the starting point for today’s idea.
What the Form 4s Actually Said
Five Costco EVPs all reported September 10 transactions, two weeks before Thursday’s report, as part of seven insider acquisitions totaling 29,749 shares over the past 90 days. Pierre Riel and Caton Frates each reported 4,552 shares acquired at $0.00, which those filings describe as restricted stock units earned under performance conditions rather than open-market purchases. The eight sells in the same window, totaling 15,407 shares for $9.2 million, look routine by any measure. Five simultaneous Form 4s do not.
The word “cluster” matters here. A single executive purchase can be noise, compensation-linked, or mechanical. Five EVPs filing on the same day, two weeks ahead of a scheduled earnings release, is a different signal entirely, but it is not the same as five executives choosing to buy stock on the open market with their own cash. In this case, the filings indicate earned equity awards, plus share withholding for taxes, which is a lower-conviction datapoint than discretionary buying.
The quarter delivered. Costco reported earnings per share of $6.75. Net sales for the quarter were $93.9 billion, and total revenue was widely reported at about $95.7 billion. Comparable sales grew 9.4%, with digitally enabled comparable sales up 19.5%.
One correction on the details: the $5.907 billion versus $5.323 billion figure refers to annual membership fee revenue in fiscal 2026 versus fiscal 2025, not a quarterly line item.
The Wider Signal in Tech
Costco’s cluster filing does not exist in isolation. A record 28 executives at companies within the Technology Select Sector SPDR ETF (XLK) have purchased their own stock on the open market over the past six months, the highest count on record according to SentimenTrader. That surpasses the previous record of 25 insiders set in 2011.
The critical distinction: these are open-market purchases reported through SEC Form 4 filings, not stock option exercises, restricted stock grants, or compensation awards. When executives receive stock as part of their compensation package, they are not making an investment decision. Open-market purchases require them to spend their own cash under the same market conditions as every other investor.
Meanwhile, EPFR analysts wrote that “insider activity suggests executives are not especially eager to increase their exposure at current valuations” for the broad market. The record XLK buying and Costco’s earnings-driven strength diverge sharply from that aggregate.
The Market Context and the Options Opportunity
U.S. equities fell this week as Treasury yields moved higher on concerns that more Federal Reserve rate hikes may be coming, but the specific index level cited in the draft does not match public S&P 500 data and should be treated as illustrative rather than a precise close. Separately, several widely followed market recaps described the 10-year Treasury yield hitting its highest levels since 2007 in mid-September 2026; the draft’s claim that the 30-year yield ended at its highest level since 2004 is not consistently supported by mainstream reporting from this month and has been softened accordingly. COST itself has been down in the high single digits over the past 12 months, depending on the measurement date.
That is the opportunity. A stock that delivered $6.75 EPS on roughly $95.7 billion in revenue, supported by a burst of insider activity in the pre-earnings window, is sitting at a meaningful discount to the consensus analyst target of $1,088.89. The yield-driven pullback across the broader market has compressed COST further, widening the gap between what the business is doing and where the stock trades.
The preferred approach here is a bull call spread expiring in November, allowing time for the post-earnings reaction to settle and the thesis to develop, while keeping premium risk defined from entry. Buying the at-the-money call and selling a strike near $960 captures the first move toward the technical resistance zone while limiting the cost of the position. A yield shock can reset the whole market, but it cannot reset a membership renewal rate or a 9.4% comp print.
The Beast Verdict
Insider activity ahead of a confirmed earnings beat, combined with elevated open-market buying across XLK names and a stock trading well below analyst consensus, is not a frequently occurring combination. The Form 4s filed over the next week across the market remain a clean live conviction test available. Watch them. When multiple executives at the same company file in the same week before a report, then the company delivers, the defined-risk case to own upside can be earned, but the highest-conviction version is still discretionary, open-market buying.
Thesis risk: a further spike in long-duration yields could cap multiple expansion regardless of fundamentals. Size accordingly and let the spread define the loss.