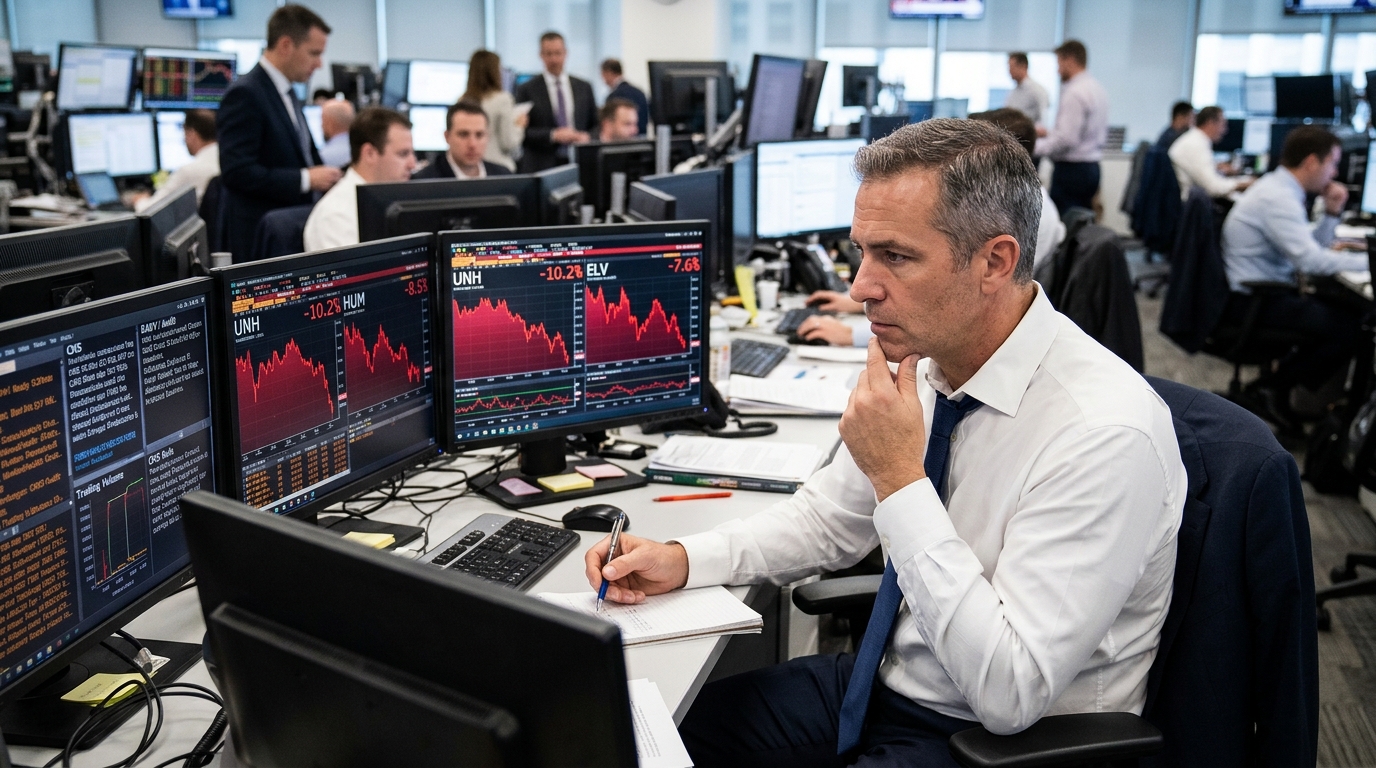
Wednesday was not a normal selloff. Managed-care shares fell harder on the second day of selling triggered by the CMS proposal to expand Medicare Advantage RADV audits, with no new filing or government action behind the deeper slide. Elevance fell 7.63%, Centene 7.03% and CVS Health 5.20%, and the selling spread to hospital and dialysis operators HCA and DaVita. UnitedHealth plunged 10.21% and single-handedly dragged the Dow down by 561 points. Humana fell 12.98% to close at $385.78, leading the S&P 500 declines.
That second-leg acceleration matters. When a group sells harder on day two without fresh news, the market is not reacting to information anymore. It is processing forced exits from crowded longs. That dynamic changes how you approach the trade.
What the Rule Actually Does
CMS released the Comprehensive Regulations to Uncover Suspicious Healthcare (CRUSH) proposed rule on November 16, 2026. It addresses the administration’s priority to prevent and address fraud, waste, and abuse across Medicare, Medicaid, CHIP, and the Marketplace. The Federal Register is scheduled to publish it today, November 19, 2026, and CMS says comments are due January 19, 2027.
The provision doing the most damage is the Medicare Advantage RADV extrapolation. The CRUSH rule would codify that CMS will extrapolate audit findings starting with payment year 2018 audits and would not apply a fee-for-service adjuster. CMS estimates that the revised audit methodology could recover an average of approximately $9 billion per payment year in Medicare Advantage overpayments. That is a per-year figure, applied across the whole industry, tied to extrapolation beginning with payment year 2018 audits.
The $90 billion is not a broad cleanup of phantom hospice enrollments, even though those are the examples CMS used to sell the rule. In CMS’s impact summary for the proposal, the quantified provisions are estimated to produce nearly $90 billion in federal budget savings from 2027 to 2036.
Who Carries the Most Risk
No insurer is more exposed than UnitedHealth. Premium revenues from CMS represented 44% of UnitedHealth Group’s total consolidated revenues in 2025, most of which were generated by UnitedHealthcare Medicare & Retirement. Humana has the most riding on it proportionally: it reported 2025 revenue of $129.664 billion, and its business is heavily concentrated in government programs.
Elevance and Centene have more Medicaid exposure, which helps explain their comparatively smaller declines. CVS carries the risk primarily through its Aetna unit. The synchronized selling suggests institutional investors pulled back exposure to the entire healthcare plans space rather than rotating between individual names.
The Trading Plan
Forced liquidation creates two distinct opportunities. The first is tactical: some sell-side desks have framed the managed-care selloff as an overreaction, citing political and funding hurdles and likely legal challenges to the audit changes. Nothing in the proposal is in effect. CMS will accept comments for 60 days after Federal Register publication, and the agency will weigh those comments before issuing a final rule on an unannounced timeline. A rule still open for comment is not a rule that hits earnings next quarter.
The second opportunity is structural. If the rule survives its comment period and legal scrutiny, it permanently compresses the economics of Medicare Advantage. That changes the long-term valuation floor for the whole group.
UNH closed at $349.91 Wednesday, its lowest point in several months. The key level to watch on a stabilization trade is whether volume begins contracting on down days. The real catch is the look-back to payment year 2018 audits, since no bid covers past years. That retroactive exposure is the reason a simple bounce trade carries asymmetric risk. Any position sized for a mean-reversion pop needs a hard stop built around the assumption that a final rule, if it comes, removes the floor entirely.
Monitor the comment letter volume after today’s Federal Register publication. Heavy opposition from insurers and provider groups is the first signal that this rule faces the same legal fate as prior Medicare Advantage RADV disputes. That is where the thesis firms or breaks.