Market Snapshot
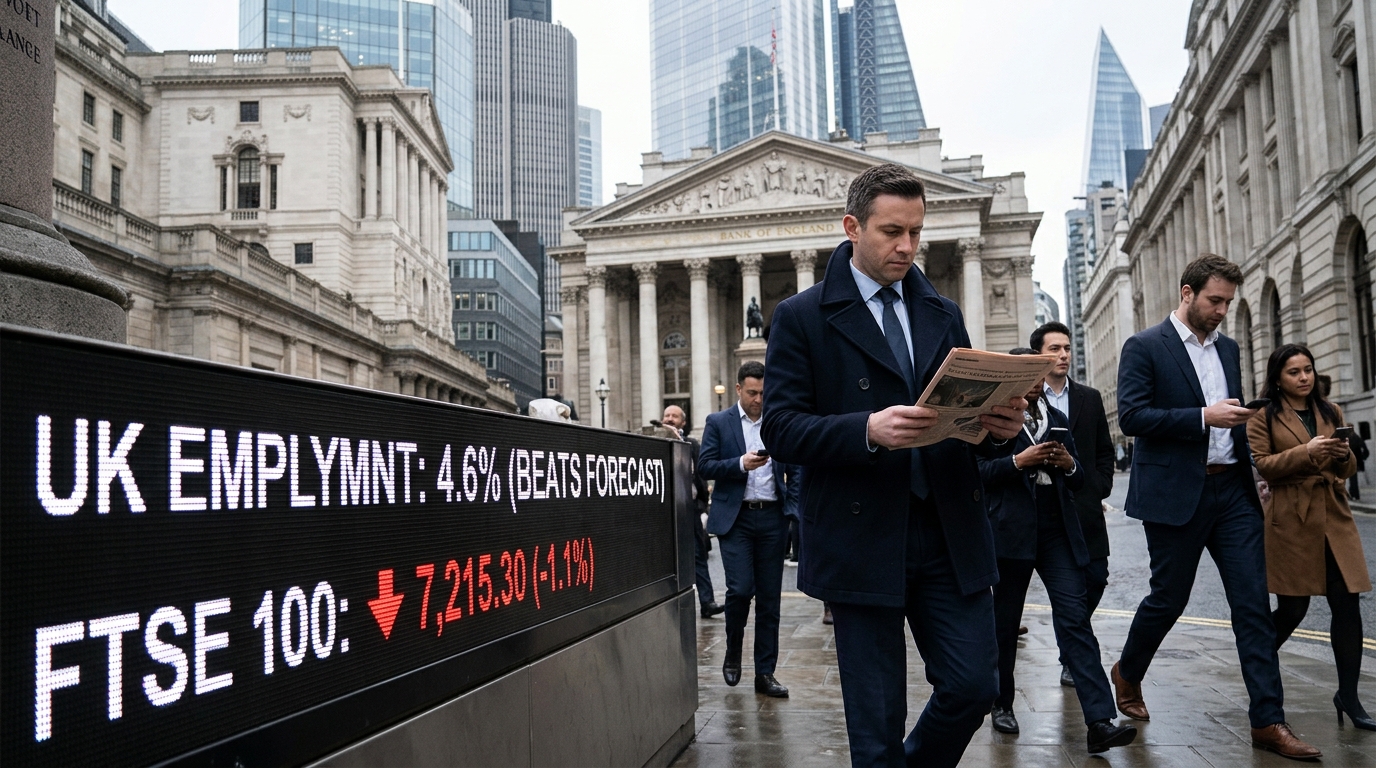
British unemployment came in at 4.6% for the three months to September, below the 4.7% forecast, but the ONS said the move partly reflects Labour Force Survey sample rotation rather than a clear lift in demand. Regular earnings growth slowed from 3.7% to 3.5%, below expectations, while total pay growth eased from 3.8% to 3.6%. The headline beat did not reassure traders. The FTSE 100 dropped about 0.7% to roughly 10,806 in early European trading.
Stocks in Focus
The headline figure masks a stalled jobs market, with vacancies at their lowest level since 2014 outside the pandemic, and real pay growth close to flat. Payroll employment fell 34,000 in October and vacancies stayed near their lowest non-pandemic level since 2014 as wage growth slowed. Domestically exposed names bore the brunt: the FTSE 250 fell, reflecting concerns about the outlook for the UK economy and the impact of elevated borrowing costs on businesses and consumers.
Sector Watch
Employers reported that higher labour and operating costs were affecting hiring decisions. Consumer-facing and retail names are under the most pressure. Adjusted for inflation, real pay grew by just 0.2% for regular pay and 0.3% for total pay, leaving household spending power effectively flat. That is a headwind for mid-cap consumer stocks regardless of what the headline unemployment rate says.
Catalyst Calendar
- Wednesday, Nov 18: UK CPI for October. Market attention shifts to Wednesday’s UK inflation report, which could determine sterling’s next major direction.
- December 17: Bank of England rate decision. As of November 16, overnight index swap pricing implies roughly a low-90% probability of a BoE hike at the December 17 MPC meeting, with a market-implied move of about +23 basis points from the current Bank Rate of 4.00%.
Technical Radar
The opening decline leaves the FTSE 100 below the 10,900 level reached last week, when the index recorded a three-month closing high. That prior high is now resistance. Support sits near 10,791 to 10,802, the range the index was testing through the morning session. A close below that zone would confirm the recent high as a failed breakout.
GBP/USD bounced from the 1.3174 pivot zone after UK unemployment fell to 4.6%; sterling keeps a slight bearish lean below 1.3252, and a close below 1.3174 would open 1.3137.
Risk Radar
Declining payroll employment, falling vacancies and slower wage growth suggest labour demand and pay pressures are easing, despite the better unemployment headline. The risk is that markets are treating a sample-rotation quirk as evidence of genuine resilience and have priced December’s hike too aggressively. The next BoE decision is on December 17. Wednesday’s CPI print is now the decisive input.
The Cheat Sheet
- Top Market Theme: A UK jobs beat that the market does not believe, with payrolls and vacancies pointing one way and the headline rate pointing the other.
- Stock to Watch: FTSE 250 consumer names. Real wage growth near zero and employer caution on hiring are a direct margin and volume threat.
- Sector to Watch: UK domestic financials. The Bank of England is monitoring persistent price pressures, with Wednesday’s consumer inflation release expected to provide further insight into whether additional interest rate increases may be required.
- Biggest Risk: Wednesday’s CPI surprises to the upside, cementing a December hike and extending the FTSE 100’s decline below 10,800.
- Biggest Opportunity: If CPI prints soft and reinforces today’s wage slowdown, rate hike expectations could ease fast and sterling-sensitive exporters in the FTSE 100 stand to benefit.
- One Thing to Remember: The ONS said the improvement in headline unemployment was partly driven by Labour Force Survey sample rotation rather than stronger underlying labour demand, because the group leaving the survey had unusually low employment and high unemployment compared with the new group entering. Trade the data the market sees, but know what it does not show.