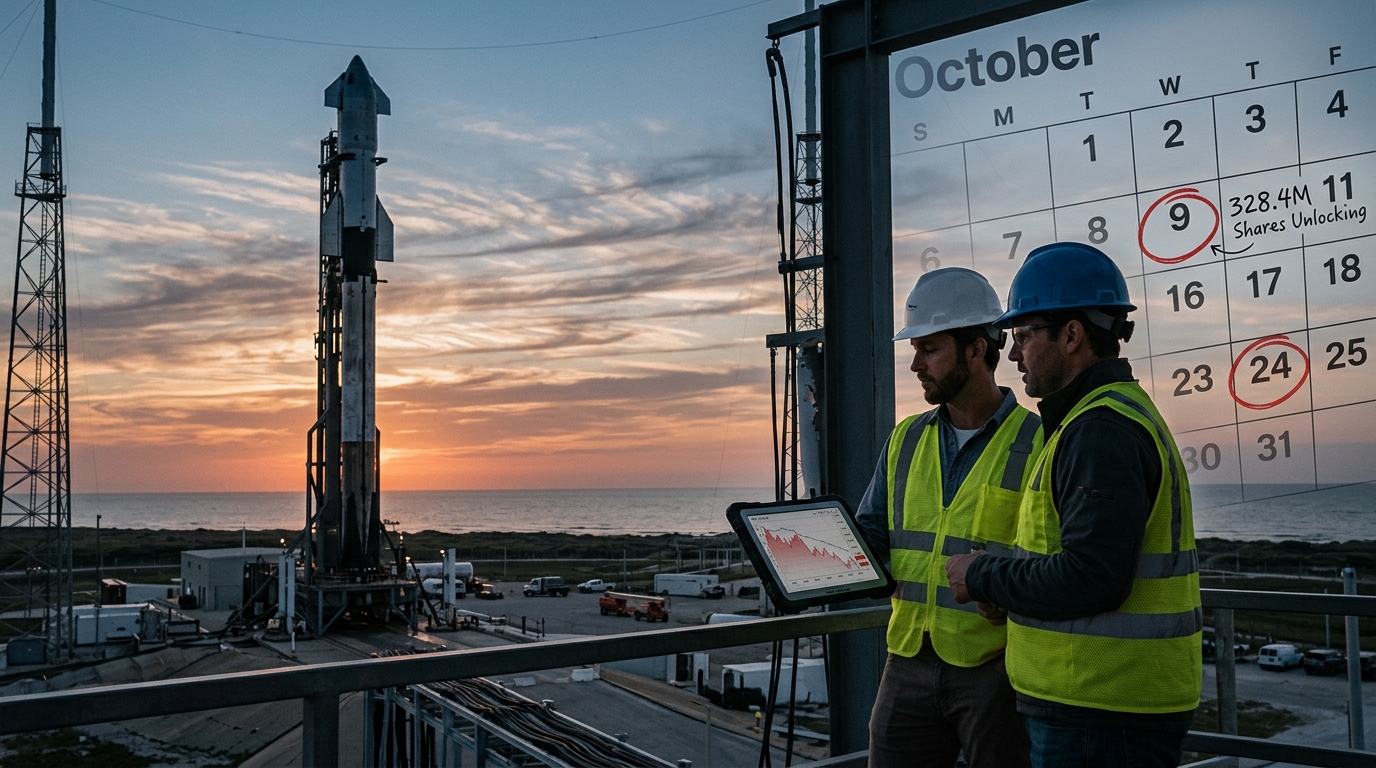
Most stocks pull back for reasons nobody can predict in advance. SpaceX is not most stocks right now. SPCX is trading around the high-$140s to low-$150s this month, against a 52-week high in the mid-$220s and a low near the low-$100s. That roughly 34% discount from the peak is notable. What makes it tradable is the reason behind it: a published, prospectus-documented supply schedule that tells you almost exactly when the pressure will arrive.
The Supply Calendar Nobody Is Ignoring
The main 180-day lockup tied to the June 11, 2026 prospectus date lands on December 8, 2026. But the release does not land in one block. Fixed-date tranches permit up to another 7% of locked shares on each of August 20, September 9, September 24, October 9, and October 24, 2026. The September rounds have already cleared. Up to 328.4 million new shares are scheduled to become eligible for sale on both October 9 and October 24. After that, an additional roughly 28% can release on the second full trading day following Q3 2026 earnings results, with December 8 as the final fixed point for the standard 180-day pool.
The numbers compound quickly. Bloomberg has reported that additional shares are expected to become eligible through October, with a much larger release tied to Q3 earnings. Elon Musk’s approximately 6.4 billion shares are subject to a 366-day lockup and are not part of the 2026 schedule. His stake does not hit the market until June 2027.
One signal worth tracking: SpaceX President and COO Gwynne Shotwell filed to sell 342,170 shares, with the proposed transaction valued at about $52.5 million. The sale falls under a Rule 10b5-1 trading plan Shotwell adopted on June 23, 2026, which limits the signal as a read on conviction. Still, the last lockup date on September 9 coincided with about a 4% down session for the stock, and the October dates carry comparable or larger share counts.
The Offsetting Force: QQQ Has to Buy
Lockup supply is only half the picture. Bloomberg reported that SpaceX will represent 2.82% of the Nasdaq-100 after the quarterly rebalance, more than doubling its prior 1.28% weighting. A JPMorgan estimate circulated in the press put potential passive buying from index funds and ETFs such as QQQ in the mid-teens of billions of dollars, depending on final weight and assets tracking the index. Other desks have suggested the adjustment could be larger if pro forma weights shift with price moves.
That mechanical demand does not cancel supply pressure on any given unlock date. When SpaceX joined the Nasdaq-100 in early July, reports at the time pegged passive demand in the low single-digit billions of dollars, yet the stock still fell sharply in the sessions around the change, in line with the usual pattern where traders position ahead of known index events and sell into the passive demand. The pattern repeats: passive demand gets front-run, then absorbed.
The Options Angle
The trade thesis here is not a directional bet on SpaceX as a company. It is a bet on volatility compression between now and each dated unlock. A put debit spread expiring just after October 9, centered near current levels, lets a trader define maximum risk to the premium paid while capturing downside if history rhymes with September 9’s roughly 4% drop. The spread structure matters: outright puts on a stock with this much lockup uncertainty can carry elevated premium, so financing the long put by selling a lower strike keeps cost manageable.
For traders who want to bridge all the way to December 8, a calendar spread offers a different expression. Selling a nearer October expiry against a longer December position can monetize the higher near-term implied volatility around the October 9 and October 24 dates while keeping exposure into the final full unlock. SPCX’s implied volatility percentile has been reported in the 20s recently, indicating options premiums have been below average versus the recent lookback window, which makes buying premium more attractive than selling it into these known events.
The Beast Verdict
SpaceX is a generational business. That is not the debate. The debate is whether the stock can hold the mid-$140s through two more supply events totaling up to 656.8 million shares in the next four weeks, followed by the largest earnings-triggered release yet. Rather than one cliff, SpaceX uses a staggered release, with the biggest tranches tied to earnings reports. That stagger is precisely what creates tradable windows. The known dates on October 9 and October 24 give defined-risk options strategies a calendar to work against. Watch volume in the two sessions before each date. If selling accelerates ahead of the unlock the way it did in September, the put spread pays. If passive QQQ demand absorbs the flow without a break, the position expires with a capped loss. Either way, the risk is defined before the trade begins.