Editor’s Note: With the market in turmoil, one of America’s best connected financial insiders (who called the 2000 and 2008 crises) is stepping forward with a warning everyone in our country needs to hear. Click here to get it or read more below.
Dear Reader,
A millionaire Wall Street insider just issued a dramatic new warning – and every American with money in the stock market needs to hear it today.
After running his own $200 million hedge fund firm, this Wall Street legend saw the Twin Towers fall on 9/11… the banks collapse in 2008… and the economy grind to a halt in 2020…
But now, he’s warning:
Whitney Tilson, who famously called the Tech Wreck in 2000, has a long history of eerily accurate predictions – CNBC even gave him a nickname he never asked for: “The Prophet.”
His appearance on 60 Minutes exposing the 2008 financial crisis even won an Emmy.
But he says what’s happening in America today is more dangerous than anything he’s seen before.
He’s warning millions of Americans could soon be blindsided by a permanent change coming to our country, which will be far more wide-reaching than a stock market crash or banking collapse.
Just look at what’s happening inside Gartner. For decades, it’s been at the heart of America’s white-collar economy – full of staff from top-tier Ivy League schools.
It should be one of our country’s most stable firms…
And yet, in the last year, it’s collapsed by more than 60%.
That’s why Tilson says it’s now critical you move your money today – because the next part of this story is going to make America unrecognizable.
In fact, he’s just agreed to reveal exactly where to put your money today – a new investment research vehicle his team spent years developing, ready for this moment.
Get the full details right here, while you still can.
Regards,
Matt Weinschenk
Publisher and Director of Research, Stansberry Research
P.S. Gartner isn’t the only white-collar firm in trouble. The world’s most powerful “knowledge” work firms are getting destroyed. Consulting firms. Insurance analytics. Software stocks.
Morningstar. Duolingo. Verisk. Accenture. They’re all in freefall. Duolingo has already collapsed as much as 75% in a year.
These aren’t just random examples. They’re connected. They’re warning signs. And ignoring them will be catastrophic.
Humana Gapped 7%. Now CMS Holds the Next Card.
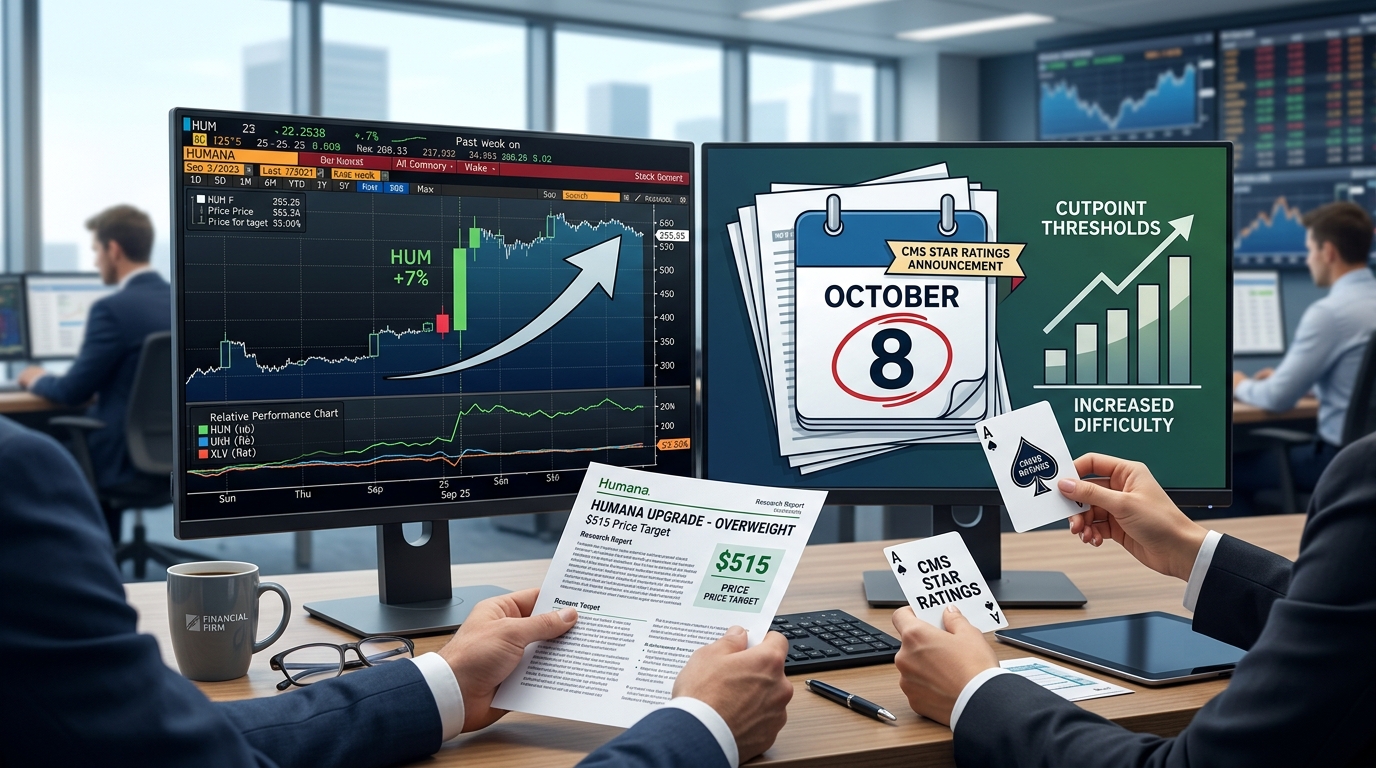
Barclays doesn’t move off the sideline quietly. On Friday, September 25, analyst Andrew Mok lifted Humana from Equal Weight to Overweight and raised his price target from $407 to $515, a 27% jump in target that sent the stock up about 7% on the session. UNH was down on the day while XLV was slightly up, reinforcing that the move was Humana-specific rather than a broad managed care reappraisal. That isolation matters. When an entire sector is bid up, a single name’s move can be noise. When one name detaches, something specific is being priced.
What’s being priced is October 8. That’s the expected public release window for 2027 Medicare Advantage star ratings on Medicare Plan Finder, and the upgrade reflects increased confidence in Humana’s upcoming Medicare star ratings, which could materially enhance the company’s contract bonuses and stock performance. This is not a vague macro bet. It is a binary event in a known time window, with Humana as arguably the most exposed large-cap name in the group.
Why the Star Ratings Are the Only Thing That Matters Right Now
Medicare Advantage star ratings determine whether a plan qualifies for federal quality bonus payments. A single half-star swing can move large amounts of bonus revenue for a big contract. That’s the lever Barclays is pulling on.
Here is what makes this year’s release particularly high-variance: the cutpoints moved, and in many measures they moved higher. Some industry analyses of the draft 2027 cutpoints have described a split across measures, with a meaningful share getting tougher, some unchanged, and a smaller share easing. HEDIS thresholds are not arbitrary, the star ratings are not a test a plan passes or fails against a fixed bar; they are set using cut points that can shift year to year based on industry performance. Plans that kept pace with the industry improve. Plans that didn’t, even if their absolute performance rose, can slip.
Plans that can’t clear the four-star bonus line can face real pressure, since a low rating strips away the extra federal money that helps fund the richer benefits Medicare Advantage is known for. For Humana, whose turnaround thesis rests heavily on recovering star-rating-linked bonus revenue, a favorable release could validate everything Mok wrote in his upgrade note. An unfavorable one breaks the thesis before open enrollment even begins October 15.
The Options Angle: Defined Risk Before a Known Binary
A stock that just gapped 7% on analyst conviction, sitting 12 days before a government data release that directly determines large amounts of bonus revenue, is precisely the kind of moment where outright stock ownership becomes a blunt instrument. The upside case, a 4-star or better outcome, could carry HUM higher. The downside case, a rating slip that undermines the Barclays thesis, could give back the entire Friday move and then some.
A bull call spread expiring mid-to-late October captures that asymmetry cleanly. Buying a call near current levels, around $410, and selling a higher strike, perhaps $450, keeps the premium at risk defined from the moment the trade is placed. The debit paid is the maximum loss. If the star ratings land favorably and the stock continues toward Barclays’ $515 target, the spread pays its full width. If CMS delivers a cold bucket of tighter cutpoints and the stock reverses, the position closes with a known, capped loss rather than an open-ended drawdown in shares.
The bid-ask spreads in HUM options are workable for a large-cap name, and open enrollment starting October 15 creates a natural timing anchor for the position. Traders should size accordingly: this is a high-conviction, defined-risk expression of a single catalyst, not a portfolio cornerstone.
What Would Break the Trade
Three things can undermine this thesis before the star ratings even post. First, a broad managed-care selloff driven by UNH, ELV, or CVS earnings commentary could drag HUM down regardless of its idiosyncratic story. Second, what remains unknown is where 2027 ratings will actually land, since draft cutpoints are not final and CMS has adjusted before. A last-minute methodology change is not unprecedented. Third, if other analysts do not follow Barclays quickly, the upgrade-driven premium could fade before the catalyst resolves.
The Beast Verdict: Humana is one of the few stocks in the market right now with a catalyst pinned to a specific time window, a clear binary outcome, and a stock that just priced sharply in one direction. That combination is where defined-risk options earn their keep. The Barclays upgrade is the argument. The star ratings release is the verdict. October 8 will tell us which side of this trade was right.