Silver and gold are obliterating all previous profit records with next-level gains now on-deck for well-timed investors.
We’re talking early-stage, small-cap discovery stories that are only just beginning to unfold.
The early-stage opportunity is taking shape across a historic North American silver-gold district that helped build early fortunes but was never explored as a unified system.
For generations, the district produced high-grade metals at surface.
Yet, the deeper story was never told – not because the metals weren’t there but because the land package was highly fragmented and never explored as a single system.
That has now changed.
For the first time ever, this exceptionally well-run small-cap explorer has brought the entire district under one roof – enabling modern geology and drilling to finally test the system properly from surface to depth across kilometers of previously untouched mineralization.
And the timing couldn’t be better.
Phase-2 drilling is accelerating as you read this… setting up a near-term flow of potential needle-moving results as the discovery picture sharpens.
And that’s not all.
Add in a second nearby district-scale silver-gold asset… and the exploration runway expands even further for this emerging small-cap.
We’ve put together a FREE online report with all the details, including:
✔ A newly unified district-scale silver-gold system in North America
✔ What the first drill results are already confirming
✔ Which targets will see drilling next
✔ How a second district-scale asset expands the discovery upside
✔ Key 2026-27 catalysts as drilling intensifies
Inside, you’ll also find our exclusive, in-depth interview with the company’s president & CEO who brings a true firsthand look at where this discovery is headed next and why the timing is so critical.
Click here to access our FREE online report and see why this Sub-US$1 silver-gold stock is setting up to be one of the most compelling early-stage opportunities of 2026-27.
Nvidia’s Next $40 Billion Order Is Signed. Who Can’t Repeat It?
Two weeks ago, AI credit looked like it was unraveling. CoreWeave’s bonds were trading at distressed levels, its five-year credit default swaps hit distressed territory, and the stock fell roughly 16% in a single session as yields on its 2031 and 2032 bonds climbed close to 15%. Oracle got dragged into the same conversation. The question hanging over Nvidia was obvious: if the buyers of its chips can’t borrow, who keeps the order book full?
Saturday night, Elon Musk answered with a $40 billion data point.
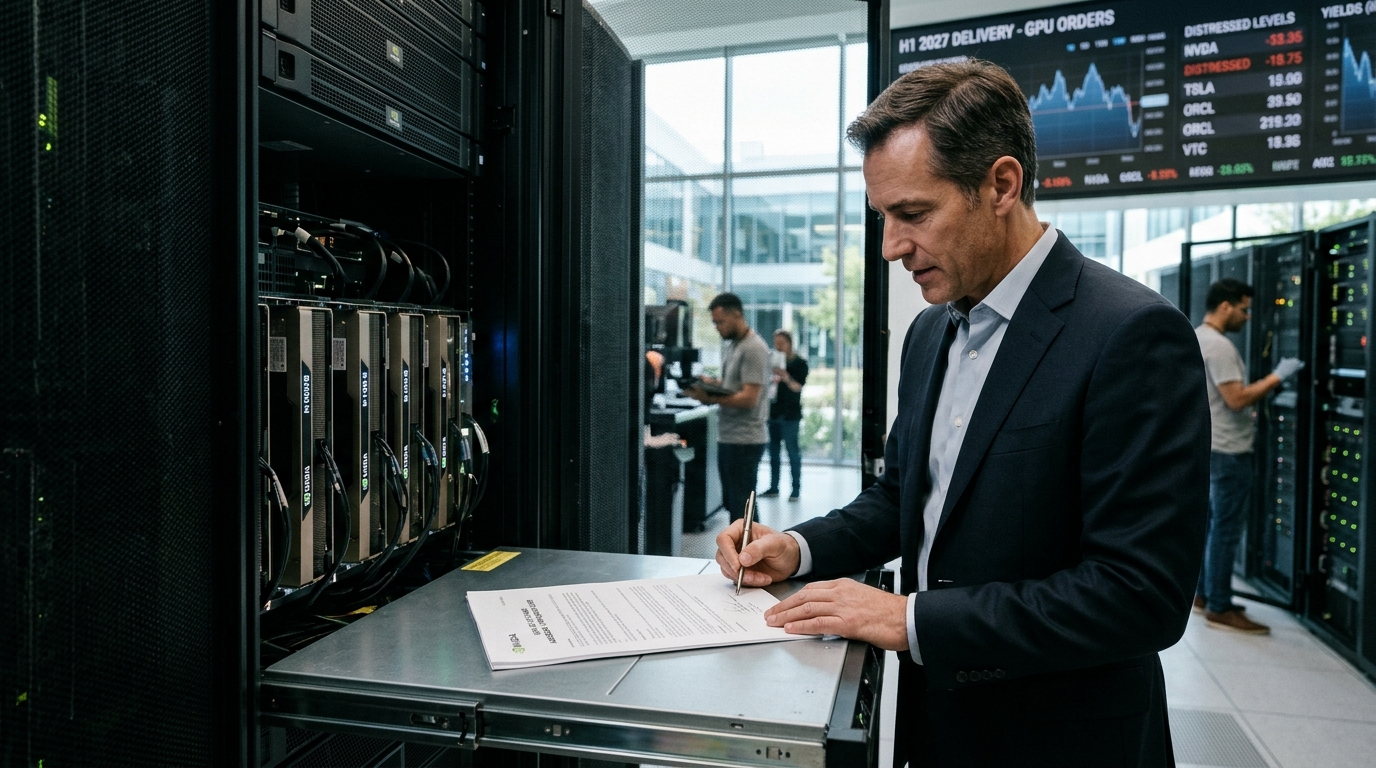
Musk said SpaceX had closed the financing, adding that the company was investment grade and generated revenue from Starlink and its launch business. In a follow-up post, he confirmed the financing primarily consisted of callable debt for GPUs expected to arrive in the first and second quarters of 2027. The deal had been in talks since early October, with market turmoil complicating financing discussions before it crossed the finish line.
That timing matters for how you read this. The deal didn’t close despite the credit stress of the past two weeks. It closed through it, and Musk was specific about why SpaceX could pull it off when others couldn’t. He wrote that debt markets have “almost entirely shut off access to money for any company that doesn’t have substantial revenue independent of AI data centers,” and that “the 200+ neoclouds are going to see guppy-level death and consolidation.”
The neocloud credit squeeze Musk described is already showing up in earnings calls. Applied Digital’s lenders were already questioning GPU residual values as collateral before SpaceX closed its deal.
That’s the real signal for Nvidia shareholders. SpaceX closed $40 billion in GPU debt because it carries investment-grade ratings and has Starlink and launch revenue, a profile almost no neocloud can replicate. The credit window is bifurcating: diversified, investment-grade operators can still access capital at scale; pure-play compute renters increasingly cannot. For Nvidia, that means demand is concentrating in larger, financially stronger hands with longer-dated purchase commitments and fewer counterparty question marks.
The GPU deliveries themselves land in Q1-Q2 2027, which is the exact window where Nvidia’s fiscal Q1 and Q2 FY2028 results will be shaped. Nvidia posted Q2 fiscal 2027 revenue of $96.2 billion, up 106% from a year ago, with Data Center revenue of $89.0 billion. The consensus for the Q3 report, due November 17, is already elevated. The SpaceX deal doesn’t add surprise revenue to that report, but it does push back against the concern that demand visibility degrades into 2027.
The options market is pricing none of this as a crisis. Nvidia’s 30-day at-the-money implied volatility has been in the low-to-mid 40% range in recent sessions, and “IV rank” readings vary by vendor methodology. The broader point still holds: premiums do not look like panic pricing into the November earnings catalyst.
The trade worth considering is a bull call spread in NVDA targeting the November 17 earnings report. With implied volatility not at extremes and a positive demand catalyst in hand, buying the move costs less than it does in true stress regimes. A defined-risk spread, perhaps the $230/$250 strikes expiring after earnings, keeps the premium outlay contained while capturing a meaningful portion of any upside if Nvidia’s data center guidance confirms what the SpaceX deal implies.
The thesis invalidates if Nvidia’s guidance signals slowing order velocity or if the SpaceX deal’s pricing terms, not yet disclosed publicly, come in at rates that suggest lenders required a steep premium for the risk. Bloomberg previously reported that market turmoil complicated pricing talks, so watch for final term disclosure.
The market spent two weeks asking whether Nvidia’s demand story held up under credit stress. A $40 billion callable debt commitment for H1 2027 GPU deliveries, closed in the middle of that stress, is the clearest answer available. The question now is whether the options market adjusts before November 17 or after it.