October 31, 2026
Four straight beats, a $3 billion quarter, and shares 20% off the high. Tuesday’s report tests whether hyperscaler AI orders are still flowing.
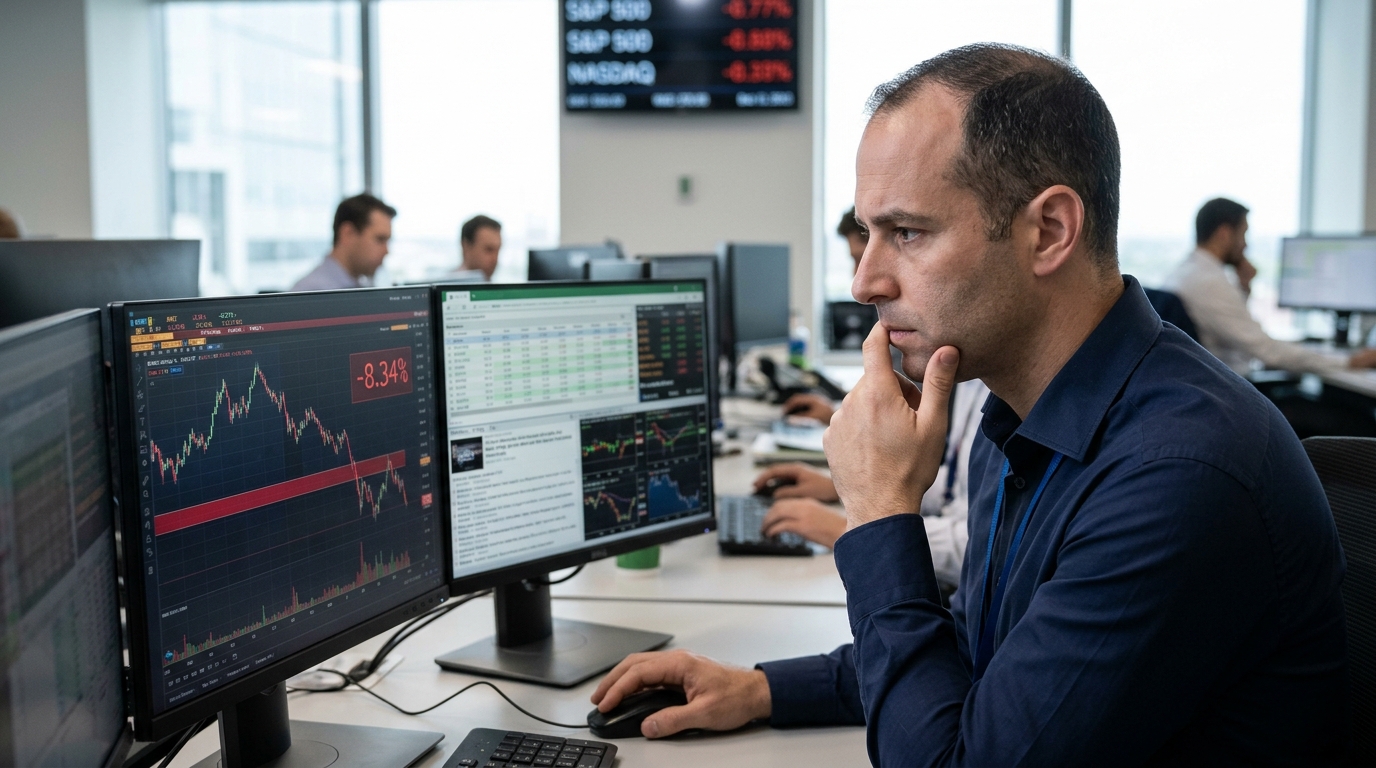
Friday’s AI infrastructure rout handed Arista Networks one of its ugliest single-session declines of the year. ANET fell 8.34% as AI infrastructure names deflated across the board, dragged lower by the same spending-skepticism cloud that hit its biggest customers. Nvidia dropped 4.22% and Broadcom shed 5.48% in the same chip selloff. None of that changes what Arista actually reports Tuesday. But it does change the options market around it.
He went 11-for-11 during the last Fed shock. Another one is about to hit.
In 2022, when the Federal Reserve made its most dramatic pivot in history and the S&P lost nearly 20%, Larry Benedict didn’t lose a single trade.
He knew where the money was going and positioned his readers to profit.
Trump is now installing his own Fed Chair, something Wall Street is already calling a generational shift.
Larry says his readers will be ready for it.
Click here to find out the one ticker he’s positioning in, completely free.
What the Business Has Built
Arista delivered 39.7% growth in non-GAAP EPS year-over-year as the company achieved its first $3-plus billion revenue quarter in Q2. Management then raised full-year 2026 revenue guidance to $12.6 billion, citing improved supply chain execution and broad-based demand across all product sectors. For Q3, management guided to about $3.3 billion in revenue, a 48% to 49% non-GAAP operating margin, and EPS of $1.06 to $1.08.
Arista has beaten consensus EPS estimates in each of the last four quarters, with surprises of 18.60%, 10.13%, 13.89%, and 8.70%, respectively. The customer base has broadened meaningfully too. Arista’s Etherlink AI fabric customer count expanded from 4 to 5 initial customers in 2024 to more than 100 cumulative customers. That is not a hyperscaler-dependent story anymore. Still, two customers, Microsoft and Meta, each account for at least 10% of Arista’s revenue on their own, which is precisely why Friday’s session mattered. Both hyperscalers have been punished for capex-heavy balance sheets with insufficient cash flow to match.
Could China be preparing a major move against the U.S. dollar?
A former Wall Street Journal finance expert believes Americans should pay attention before November 12. Discover the 5 steps he recommends.
Why the Options Market Is the Right Lens Here
Options are pricing a plus-or-minus move into the November 3 earnings release. That is a market asking a direct question: does the order book still hold when the two biggest spenders are under pressure?
The interesting wrinkle is that long options look relatively accessible despite the elevated earnings implied move. The near-term expiration carries the earnings premium; the longer-dated options do not. That term structure creates room for a bull call spread rather than an outright long call, capping the premium at risk while preserving meaningful upside if the report clears the bar.
A November 7 expiry bull call spread, buying a call near the current price around $168 to $170 and selling one roughly 10% to 12% higher, positions for Arista clearing $3.3 billion in revenue and reaffirming its AI networking goals without paying for the full implied swing. The stock has exceeded the options-implied move in six of its past eight earnings announcements, which tells you the market has historically underpriced the actual move.
5 Stocks Built for a Strong Finish to 2026
Higher interest rates, a reshuffled Washington and a market that wants proof of AI profits will all test stocks before the year is out. These 5 companies have the earnings to handle it. Download our free report for the catalysts, recent results and analyst price targets behind each one.
What Could Break the Trade
Any pullback in AI data center capital expenditures, deployment delays, or shifts toward custom internal networking architectures by either hyperscaler pose an immediate threat to Arista’s top-line trajectory. To secure hardware capacity, Arista’s purchase commitments rose to about $9.6 billion by the end of Q2, raising inventory cost exposure and risk of margin compression if component delivery schedules shift. A guidance cut or soft commentary on order cadence would punish the stock further, and the defined-risk spread structure is the correct response to that possibility. Position sizing matters: treat this as a single-event trade with a fixed cost basis.
The Beast Verdict
Tuesday’s report is the cleanest read the market will get on whether hyperscaler AI networking demand has actually cooled or whether Friday was noise. Arista heads into this report having posted its first $3 billion quarter, yet the stock has shed nearly 10% in a month while trading at a premium multiple that left no margin for error. Four consecutive beats, a customer count that has grown from a handful to more than 100 on the AI fabric side, and a company that has raised full-year guidance three times in 2026 all argue the thesis is intact. The options market’s implied move, priced into near-term expiries while longer-dated volatility stays subdued, makes the bull call spread the disciplined way to take that side. If the orders are still coming in, the stock covers that implied move in an afternoon. If they are not, the premium is all that is at risk.