September 15, 2026
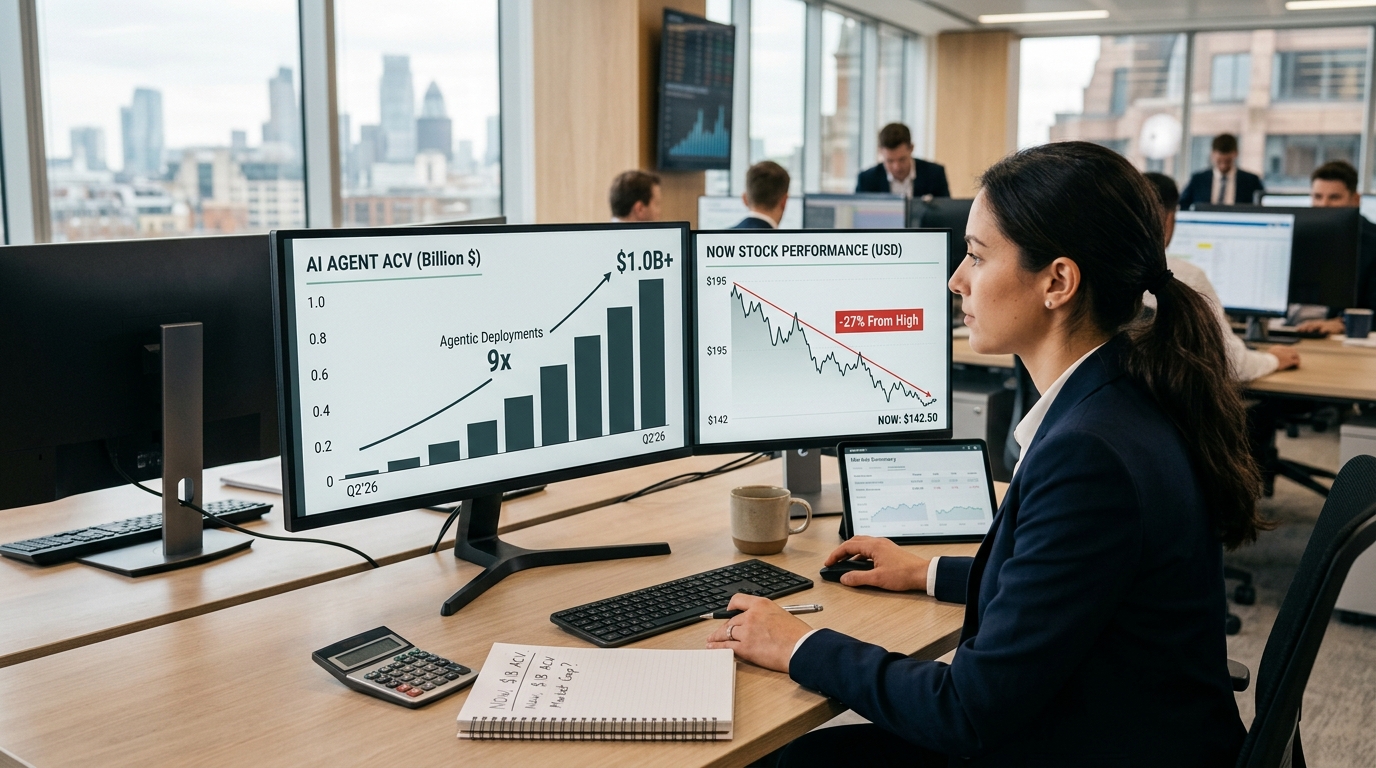
AI contract value crossed ten figures in Q2, agentic deployments grew ninefold, and NOW trades near $142. That gap is the opportunity.
Wall Street spent most of 2026 debating whether AI agents would cannibalize enterprise software revenue by replacing the human seats that generate subscription fees. ServiceNow just answered that question with numbers, and the stock has barely moved.
Most investors can’t see it. But once you do, you can’t unsee it.
There’s something hidden in the stock market.
Most people walk right past it.
But a handful of investors know how to light it up.
And when they do …
The path to gains like 387% … 756% … even 2,770% … appear as clear as day.
ServiceNow’s AI products crossed $1 billion in annual contract value during Q2 2026, a milestone that arrived alongside a beat across the company’s key reported metrics and a raised full-year subscription revenue outlook.
More telling than the dollar figure is the velocity underneath it: AI net new ACV accelerated more than 40% quarter over quarter, the number of customers running agentic AI in production grew ninefold over nine months, and deal volume among first-time agentic AI buyers rose more than 45% year over year.
The HR workflow layer is where this lands hardest. When AI agents are deployed across HR and connected systems, manual bottlenecks stop accumulating. Autonomous HR agents execute end-to-end work, involving humans only when required, to complete tasks and enhance the employee experience.
The scale behind this pitch is real, and it is coming from ServiceNow itself: 23 million employees use ServiceNow’s employee portal every month, generating an estimated 40 million-plus cases annually. The company says AI specialists across its customer base already resolve 91% of cases without reassignment. That is not a demo stat. That is the production number inside contracts already signed.
5 Nasdaq Stocks Under $5 That Aren’t What You Think
Most stocks under $5 come with a reputation. These don’t.
Each company on this list is tied to major trends like AI, cybersecurity, and next-gen infrastructure.
They may not have the spotlight yet, but they are building real businesses in real markets. That combination is not always easy to find at this price level.
Around half of net new business is now coming from non-seat-based pricing, including usage-based and consumption-driven structures. That directly refutes the SaaSpocalypse thesis. Agents are expanding the revenue surface rather than compressing it.
The Options Opportunity
On September 14, 2026, NOW traded roughly in the low-$140s, putting it about 27% below its 52-week high of $194.73. Q3 2026 subscription revenues are guided to $3.975 to $3.980 billion, representing 20.5% year-over-year growth, with cRPO expected to grow about 19.5% in constant currency year over year and the company flagging an estimated ~$35 million year-over-year FX headwind to Q3 2026 cRPO.
Earnings land late October, and the HR agentic buildout gives management another concrete data point to put in front of analysts.
A bull call spread targeting the October 23 expiration, structured in the $142 to $160 range, keeps risk defined at the premium paid while capturing a move back toward the upper end of what the options market is already pricing as probable.
Nuclear Energy’s Comeback Could Spark Before 2026
Global energy demand is surging and one overlooked power source is quietly returning to the spotlight. New policy support and supply constraints are setting the stage for a surprising shift in the energy markets.
What Could Go Wrong
Since March 31, ServiceNow has faced an incrementally stronger U.S. dollar, with FX headwinds estimated at roughly $35 million for Q3 2026 current remaining performance obligations. That is a real drag on the reported number and could disappoint analysts anchored to constant-currency growth.
Needham raised its price target to $155 on September 11, 2026, while BTIG moved its target to $170 on September 8, 2026, so the analyst community is split on how fast the re-rating happens.
The thesis is not that NOW is cheap. It is that the HR agentic business is compounding faster than a stock sitting well off its high implies, Q3 earnings provide the next hard date to prove it, and a defined-risk spread lets you express that view without betting on direction through October.