Why Did Trump Just Ban America’s Most Powerful AI?
It’s not Nvidia. It’s not OpenAI. It’s not Google.
It’s a San Francisco AI lab whose technology is used by eight of the ten largest companies in America – and which Bloomberg calls the highest-revenue AI company on earth.
Trump banned it from every federal agency and the Pentagon blacklisted it. The reason isn’t what you think. Full details here.
AI COULD KILL US ALL!
That’s not my prediction.
It’s what people building AI are now warning.
A former Anthropic researcher just quit, saying AI labs are “gambling with our lives.”
Then Anthropic’s own alignment lead went further…
He says there’s a greater than 10% chance advanced AI could kill all humans within the next decade.
Terrifying?
Absolutely.
But here’s what caught my attention as an investor…
Washington is already treating Anthropic’s technology as a national-security issue.
And if these warnings accelerate Washington’s intervention will become inevitable.
Investors positioned before this happens stand to benefit most.
Addison Wiggin has put his extensive presentation right here…
This ad is sent on behalf of Banyan Hill Publishing.
If you would like to unsubscribe from receiving offers for Market Rebellion, please click here.
Zscaler’s 9% Drop Is Selling Pressure Worth Selling Into
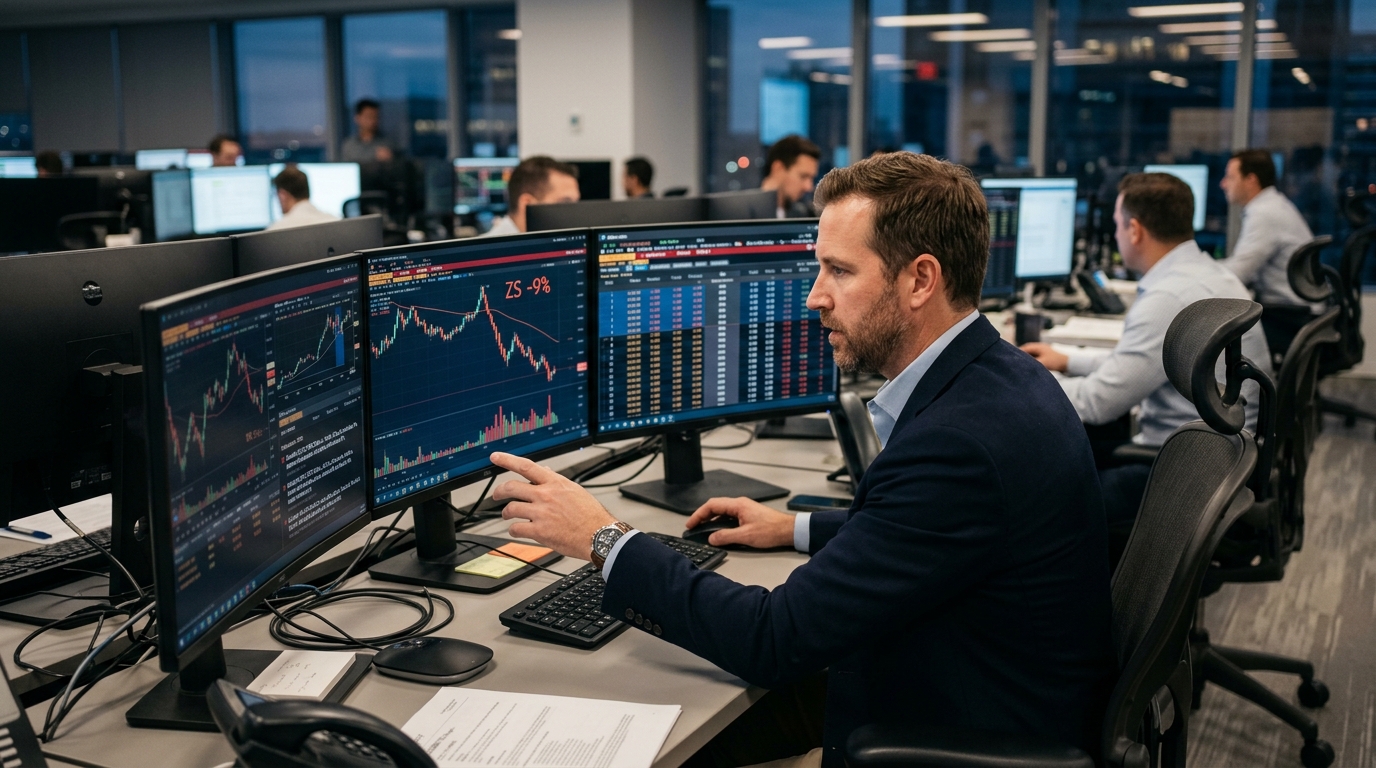
When a stock falls about 9% because a sales executive leaves for personal reasons, the right question is not whether the company is broken. It is whether the selling overshot what the news actually warrants, and whether the elevated option premium that followed creates a better opportunity on the short-volatility side than the long one.
That is exactly where Zscaler sits this weekend.
What Happened
Shares of Zscaler fell about 8.6% on Friday after the company announced that Chief Revenue Officer Mike Rich is stepping down for personal reasons. The decline extended an after-hours drop of about 4% that followed the announcement. Ross Tackett will succeed Mike Rich, who will step down as an officer effective October 1, 2026, but will remain with the company as a strategic advisor through December 31, 2026.
Jefferies said the timing raises execution risk, since the departure came after Zscaler issued its fiscal 2027 guidance and was not factored into those projections. The firm noted that Rich took roughly a year to shift the sales organization from opportunistic selling to an account-centric model, and any transition could carry a lingering impact. Still, Jefferies said it does not expect major disruption.
The Story Behind the Trade
Here is the context the Friday selloff ignored. Zscaler’s Q4 revenue rose 25% year over year to $898.2 million, beating estimates, and adjusted EPS of $1.19 topped forecasts, driven by a record non-GAAP operating margin of 24%. Net new ARR growth excluding Red Canary accelerated to 17%, up from 7% in fiscal 2025. The go-to-market machine was actually improving under Rich. His successor, Ross Tackett, was not parachuted in from outside. Tackett has been with the company for three years and brings more than three decades of technology sales leadership experience, including a proven track record of scaling multi-billion-dollar enterprise go-to-market organizations.
The guidance picture was already acknowledged as conservative before any of this. For fiscal 2027, Zscaler projected revenue growth of approximately 16.6% to 17.5% and ARR growth of approximately 16.6% to 17.4%, compared with roughly 25% growth during fiscal 2026. The outlook represents a moderation in the company’s expected growth rate. CFO Kevin Rubin said the company needs to account for sales productivity and the pace at which new products are adopted, making execution the primary issue behind the slower forecast. The deceleration was baked into guidance weeks before Friday’s filing.
Zscaler is down about 11.6% since the beginning of the year, and after Friday’s move it closed around $193. That puts it roughly 43% below its 52-week high of $336.27 from November 2025. A stock that has already given back that much ground is pricing in a great deal of bad news. Adding a CRO transition to a pile that already includes a guidance step-down and a roughly 3% workforce restructuring, and then marking the stock down about 9% in a single session, starts to look like forced de-risking rather than a fundamental reassessment.
The Options Angle
The spike in implied volatility after Thursday’s filing is the opportunity. When a defined event, such as a personnel announcement, drives a stock down sharply in one session, put buyers who chased the move late are overpaying for protection that is already largely reflected in price. Implied volatility typically reverts toward historical norms once the event is absorbed and no further negative news emerges.
The preferred strategy here is a bull put spread on ZS, targeting a strike below current levels with a defined maximum loss. The thesis does not require the stock to rally. It only requires that ZS does not collapse further on a fresh negative catalyst. Selling elevated put premium with a defined floor means time decay and volatility contraction both work in the position’s favor from day one. Zscaler’s Investor Day in New York on October 6, together with a September 9 launch webcast for the company’s Agentic SecOps solution, gives management two near-term chances to reframe the growth conversation with fresh product detail. Those events are the catalyst for a premium bleed-down.
Risk Management
The thesis weakens if Zscaler’s Investor Day on October 6 produces a guidance cut or if Tackett signals a deeper restructuring of the sales organization than what is currently telegraphed. Any broader cybersecurity sector rotation, given that peers like CrowdStrike and Palo Alto Networks have been strong in 2026, could also weigh on ZS independent of company-specific developments. Position sizing matters: this is a defined-risk trade, not a conviction that the bottom is in.
The Beast Verdict
Zscaler is a company with 25% revenue growth, a broadening AI security portfolio, and a replacement CRO who built the current sales strategy from inside. The Friday selloff was driven by sentiment, not by a change in the underlying business trajectory. Analysts have acknowledged some execution risk due to the timing but expect limited disruption, noting Tackett helped develop the current sales approach and has extensive experience. The company has not changed its fiscal 2027 guidance in connection with the CRO transition. When fear overshoots facts, elevated put premium on a fundamentally intact name is the edge. Sell the panic, define the risk, and let October 6 do the work.