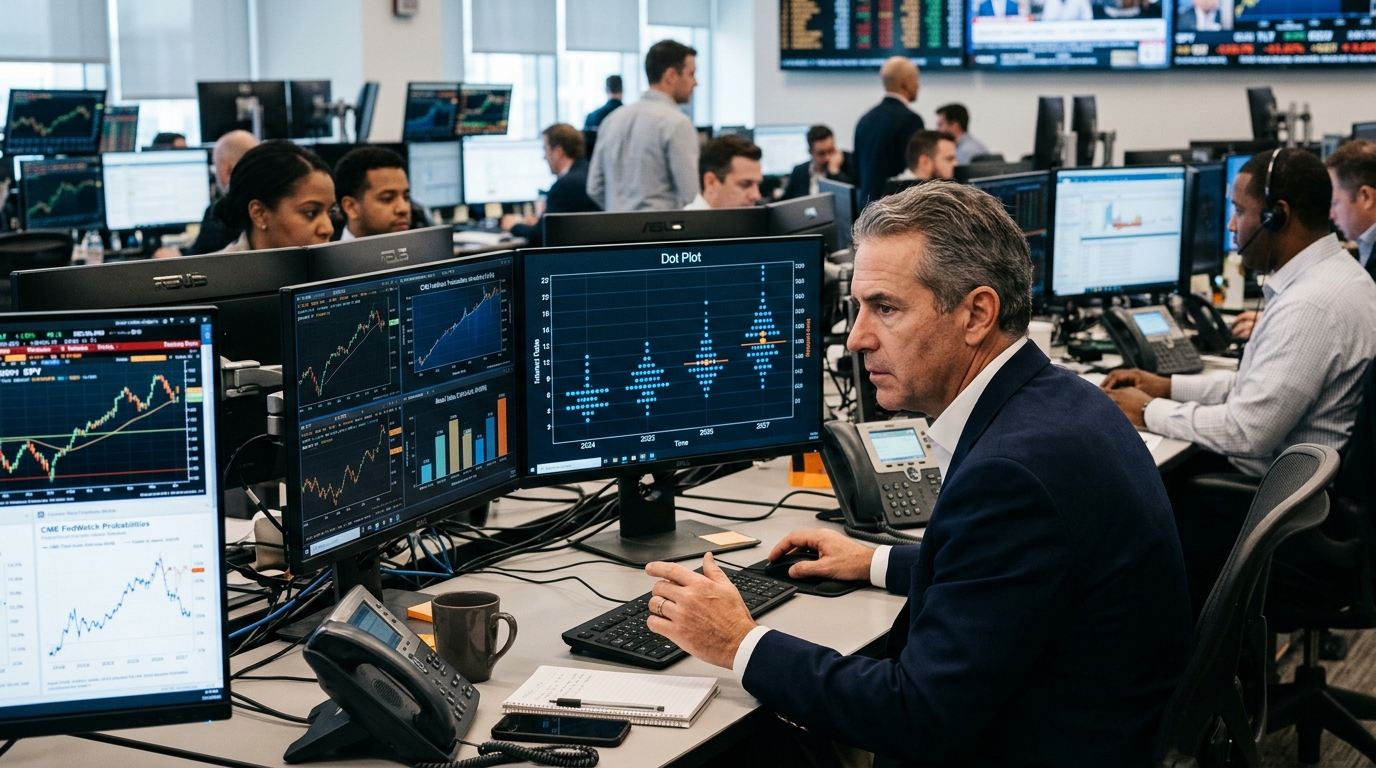
The hike itself is not the event. Markets have mostly priced a 25-basis-point increase to 3.75% to 4.00% at today’s 2pm ET decision, per CME FedWatch, which would be the first move higher since July 2023. What is not priced, and what actually determines how SPY and TLT close, is what the updated dot plot says about 2027.
Before that, traders get a warm-up at 8:30am: August retail sales from the Census Bureau, landing five and a half hours before the statement. July’s number was already soft: retail and food-services sales fell 0.6% to $763.6 billion. A second consecutive miss would add a recessionary undertone to a session already dominated by the Fed. A bounce would reinforce the “strong enough to hike, not strong enough to stop” environment that has carried the 10-year yield to its highest level since 2023.
The 10-Year Is the Problem Warsh Has to Answer
The 10-year Treasury climbed above 5% on Tuesday, reaching levels not seen since 2023, as oil prices and inflation worries kept pressure on yields. That yield is not waiting for Warsh’s permission. It is already pricing a structurally higher path.
That creates the central tension in today’s dot plot. The June median for 2027 was about 3.6%. Futures markets have moved considerably since June. If today’s dot plot revises the 2027 median meaningfully higher, toward 4.25% or above, it validates the bond market’s move and stocks face a genuine rate reset lower. If the median barely moves, Warsh risks appearing to fight a 5% ten-year with a single quarter-point hike and no credible follow-through path.
One more complication: Warsh did not submit a dot in June, and he has publicly criticized forward guidance as a policy tool. The press conference, not the dot chart, may carry more weight than usual.
What Gets Rate Reset and in Which Direction
Banks (XLF) are the cleanest expression of higher-for-longer. Net interest margins expand when the front end rises, and a hawkish 2027 median accelerates that math. The sector gained about 1.4% in August even as broader markets struggled with rate anxiety. It is already partially positioned for this outcome.
Homebuilders face the opposite dynamic. The ITB index is anchored to mortgage rates, which track the long end more than the funds rate. A 5% ten-year that the dot plot confirms as durable removes the 2027 easing timeline the sector has been leaning on. Analysts have warned that multiple rate reductions are needed to fully revive housing demand, and a hawkish plot pushes that clock further out.
Utilities and small caps are the clearest losers if Warsh delivers a hawkish surprise. XLU fell 4.8% in August alone as the long end climbed, and the iShares Russell 2000 ETF (IWM) has already broken below its September 1 low, forming a series of lower highs and lower lows. Small caps carry significant floating-rate debt. Every additional hike compounds refinancing pressure on balance sheets that cannot absorb it the way large-cap technology can.
The Manufacturing Signal You Cannot Ignore
Tuesday’s Empire State Manufacturing index dropped 13 points to 7.6 against a consensus of 14.75, well below August’s reading of 20.6. The headline cooled sharply, but the prices paid subindex rose five points to 63.1, edging above its recent four-year high from May. Growth is slowing while input costs are accelerating. That is stagflationary in character, and it is the environment Warsh is hiking into.
The Trading Plan Around 2pm
The hike alone changes nothing. It is already in prices. What matters is the 2027 dot median and Warsh’s tone on whether today’s move is the beginning of a sequence or a single adjustment.
A 2027 median at or above 4.25%, combined with hawkish press conference language, pressures TLT further, rewards XLF, and hits IWM and homebuilders hard. A flat or dovish median, one that suggests today’s hike is close to sufficient, would likely produce a TLT relief rally and a rotation toward rate-sensitive names that have already been punished.
The highest-conviction position into the announcement is to watch how the 10-year reacts in the first 15 minutes after 2pm. If the yield holds above 5% despite the hike, the bond market is telling you the dot plot was not hawkish enough to matter. If it pulls back below 4.95%, Warsh gave the long end something to work with. That yield is the clearest real-time read on whether today’s decision is priced to hold, or priced to follow.