Dear reader,
Most investors wait for the government press conference.
I follow the money before the cameras show up.
And the money trail now leads straight to one tiny nickel stock.
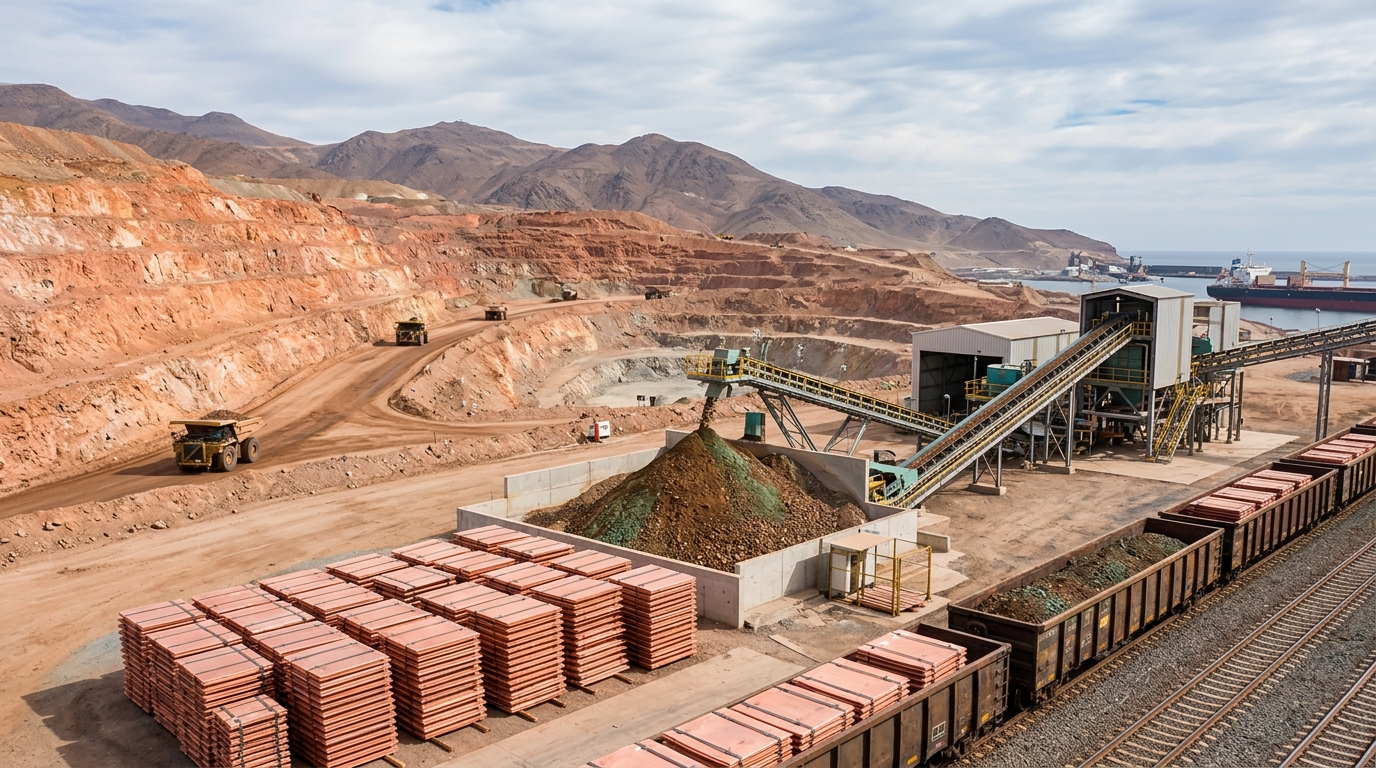
Its U.S. platform has already been selected for $135.4 million in disclosed federal grants: $114.8 million tied to a domestic processing facility and another $20.6 million supporting exploration in Minnesota and Michigan.
That is not a prediction. That’s money already disclosed.
The next step is my forecast: I believe Washington could eventually go further and take an equity stake.
It may never happen. But the U.S. has already shown it is willing to put taxpayer capital directly into strategic mineral companies. And this company now controls the only primary nickel mine operating in America.
Meanwhile, Tesla has locked in a six-year supply agreement, and America remains dangerously exposed to foreign nickel supply.
Russia, China, and Indonesia have leverage because the United States allowed its domestic pipeline to wither.
This little company is one of the few credible ways to fight back.
That’s why I bought 10,000 shares before any equity announcement.
I am not promising Washington will buy in. I am saying the grants, the operating mine, the Tesla agreement, and the strategic pressure form a setup I refuse to ignore.
Click here to learn more about the $5 nickel stock I believe Washington could target next.
Yours for peace, prosperity, and liberty, AEIOU,
Dr. Mark Skousen
Macroeconomic Strategist, The Oxford Club
P.S. Washington has already backed this platform with $135.4 million in disclosed grants.
If an equity stake comes next, I believe a stock this small could move violently.
I refuse to wait for the press conference.
Click here to reveal details on what I bought before Washington makes its next move.
A $2 Billion Rare-Disease Price Tag Points to Biotech M&A
The number that matters in the Shionogi-IntraBio deal is not $2 billion. It’s $68 million.
The FDA granted Aqneursa a second approval on September 18, 2026, for ataxia-telangiectasia, and IntraBio recorded $67.9 million in net sales in 2025. Shionogi agreed to pay $2 billion for that revenue base, a multiple of roughly 29x trailing sales, all cash upfront. When a major acquirer pays that kind of premium for a drug with two indications and a third regulatory decision still pending, it tells you something about how scarce commercially approved rare-disease assets have become.
Why Shionogi Needed This Deal
Shionogi acquired IntraBio to expand its rare-disease portfolio as the Japanese drugmaker diversifies beyond its traditional focus on infectious diseases. That transformation has been deliberate and fast. The acquisition builds on Shionogi’s $2.5 billion purchase of global rights to the ALS therapy Radicava, completed on April 1, 2026. Shionogi said that transaction established a rare-disease commercial platform expected to contribute approximately $700 million in annual global sales. IntraBio slots in as the second pillar, adding neurodegenerative coverage and a pipeline that includes Pompe disease, Fragile X syndrome, and Jordan’s syndrome.
The transaction follows a label expansion for IntraBio: Aqneursa became the first approved treatment for ataxia in patients with ataxia-telangiectasia, a rare genetic disorder associated with neurodegeneration and an elevated risk of cancer. Buying within weeks of that label expansion, Shionogi paid for momentum, not just revenue.
The Trade Thesis: Who Gets Bid Next
The IntraBio price sets a floor for what commercial rare-disease assets are worth to a large acquirer that lacks them. Two listed names fit the profile closely.
Zevra Therapeutics (ZVRA) is the most direct analog. Zevra is a commercial-stage rare disease company whose lead asset, MIPLYFFA (arimoclomol), was approved by the FDA on September 20, 2024 for the neurological manifestations of Niemann-Pick disease type C. That is the same indication that launched Aqneursa. MIPLYFFA has orphan medicinal product designation in Europe, and Zevra submitted a Marketing Authorization Application with the EMA in July 2025.
BioCryst Pharmaceuticals (BCRX) is a broader but equally compelling candidate. BioCryst hit its first full year of profitability in 2025, with Q2 2026 total revenue up 34% year over year to $218.3 million, fueling acquisition speculation. Takeda often tops buyer lists because navenibart is being developed in Phase 3 for hereditary angioedema, where Takeda’s Takhzyro is a leading prophylactic therapy. AstraZeneca also comes up given its Alexion rare-disease platform. The put/call ratio on BCRX cannot be confirmed from a consistent primary source, so treat options-skew as anecdotal rather than a datapoint.
The Options Opportunity
For ZVRA, a January 2027 call spread captures the EU catalyst at defined risk, but the EMA timeline is less straightforward than it looked a year ago. The EMA’s CHMP issued a negative opinion in July 2026 and the company requested a re-examination, so the next decisive regulatory moment may be a re-exam outcome and any subsequent European Commission decision, not a clean 2027 approval path. With the stock trading near $12.40, buying the January $12.50 call and selling the $17.50 call funds the position cheaply while targeting the re-rating that any favorable European turn would trigger. Implied volatility on ZVRA is elevated relative to realized volatility, so a spread structure rather than an outright long call keeps theta manageable across a three-month hold.
For BCRX, the M&A angle is the cleaner play. A February 2027 call spread, buying the $11 strike and selling the $16, positions for a bid or a material re-rating tied to navenibart Phase 3 data without requiring full premium exposure. Any confirmed deal approach would compress that spread toward maximum value quickly.
The Beast Verdict
Shionogi just showed the market exactly what a rare-disease drug with two approved indications, a growing commercial launch, and a pending foreign regulatory decision is worth to a strategic buyer: roughly 29x sales, all cash upfront. ZVRA mirrors that profile on the U.S. commercial side, but its European regulatory path now hinges on the outcome of the CHMP re-examination rather than a simple march toward 2027 approval. BCRX offers a wider strategic appeal at a lower multiple. Both carry defined-risk call spread structures into catalysts that are weeks to months away, not years. Position sizing matters. Neither name is liquid enough to size aggressively. But the Shionogi price tag is the clearest signal of rare-disease M&A appetite seen this year, and it points directly at these two names.