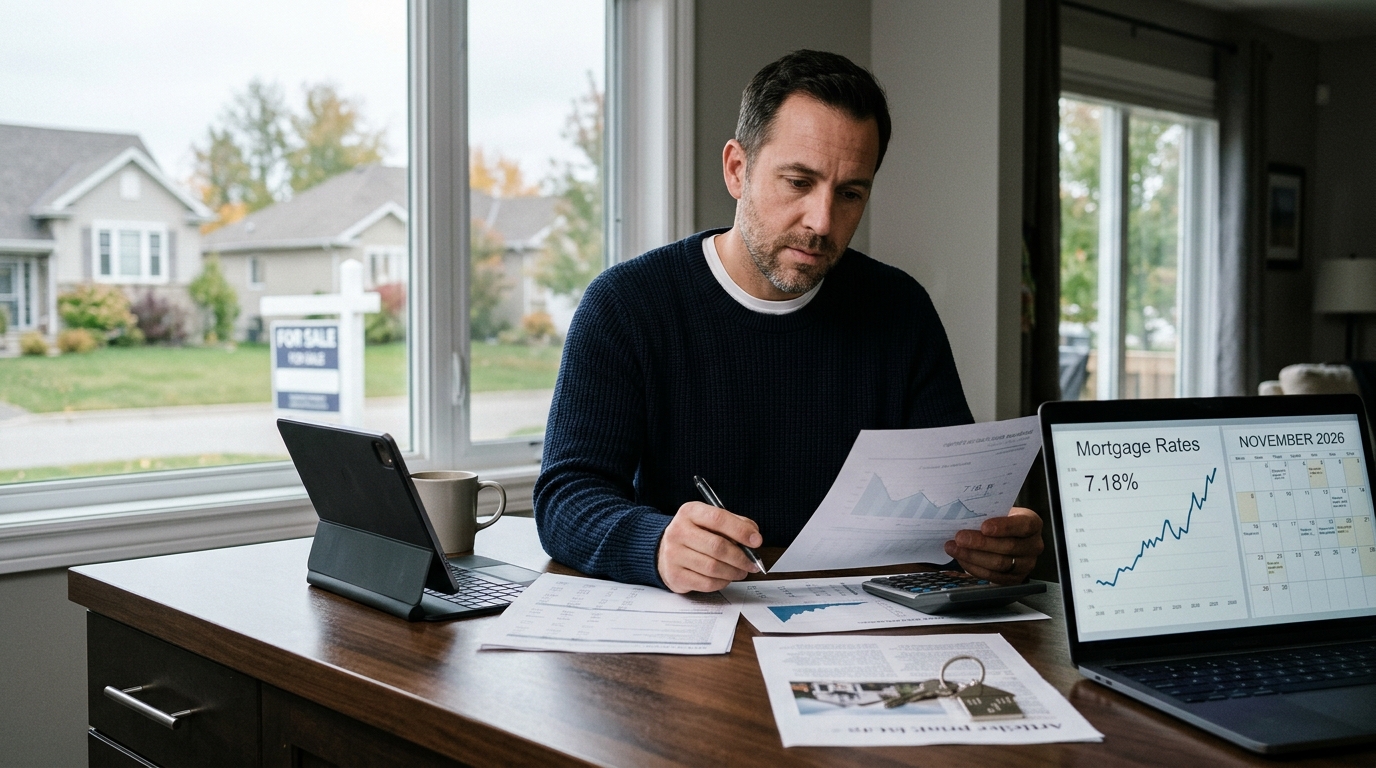
The number most buyers need to know is 7.18%. Freddie Mac’s Primary Mortgage Market Survey for the week ending November 5, 2026 put the 30-year fixed-rate mortgage at exactly that level, down from 7.24% the prior week. Three consecutive weekly declines sound like progress. They are not a trend investors should trust.
The 7.18% average is still nearly a full percentage point above where it stood a year ago, when 30-year loans averaged 6.22% and 15-year loans 5.50%. And the force pushing rates higher has not gone away.
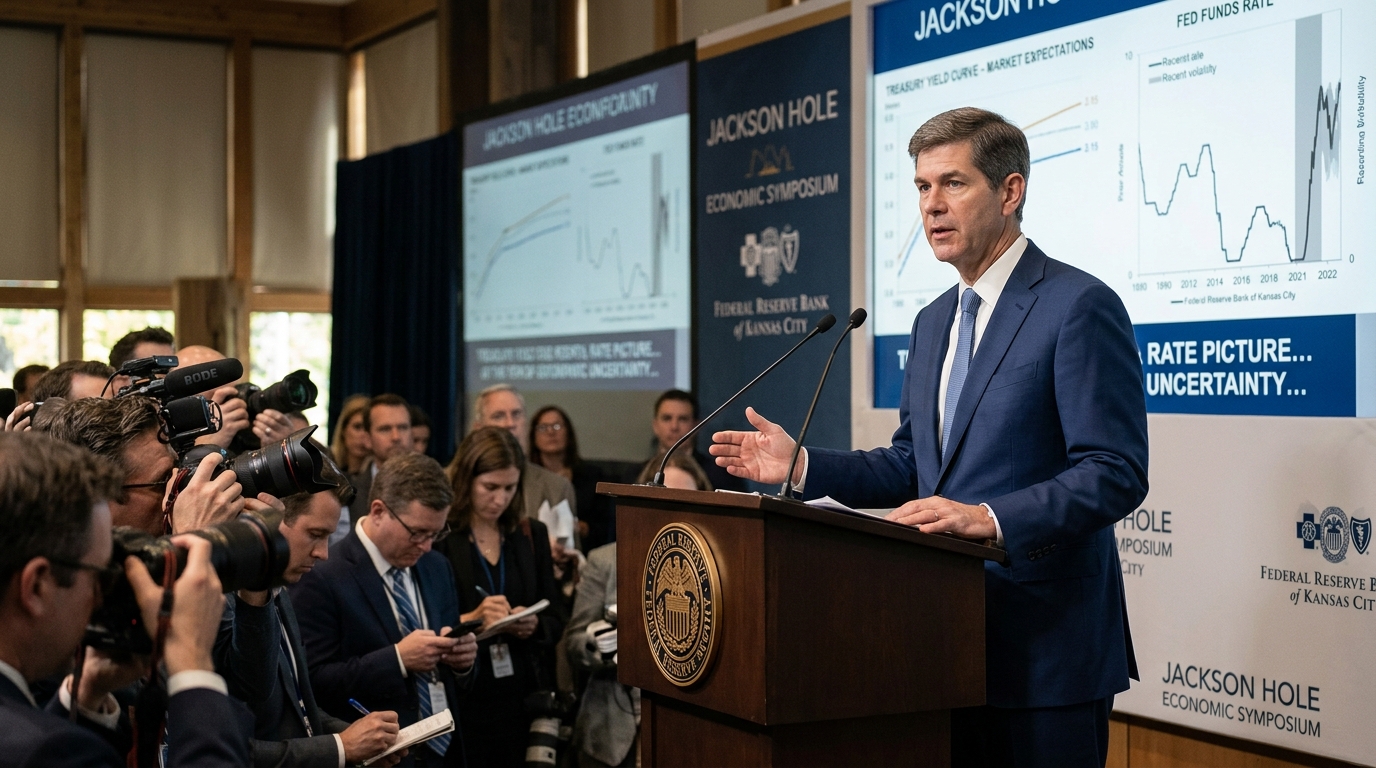
Traders raised the probability of a December Fed rate hike to the high-70% range after October payrolls rose by 165,000 and the unemployment rate fell to 4.1%. Treasury yields rose after the jobs report, with the 10-year ending November 6, 2026 near 4.86%. A labor market this strong, against still-elevated inflation, leaves the Fed little political cover to pause again.
If the Fed raises rates on December 9, 2026, the target range would move to 4.00% to 4.25%. That pushes the 10-year yield higher, mortgage spreads follow, and 7.18% starts looking like a floor rather than a ceiling.
What This Costs a Buyer Right Now
The arithmetic is straightforward and sobering. On a $400,000 mortgage, the difference between today’s 7.18% and last November’s 6.22% is roughly $260 per month. That is about $3,100 a year before taxes, insurance, or any maintenance cost. First-time buyers, the group most sensitive to monthly payment, are absorbing that increase on top of home prices that have not corrected to compensate. The housing market is hemmed in by high prices and high mortgage rates, and younger, first-time buyers are struggling to break in.
Refinancing is effectively off the table for anyone who locked a rate below 5% between 2020 and 2022. The incentive to move, to trade up, to access equity through a cash-out refi, all of it is locked away behind that rate differential. That is part of why existing-home supply remains anemic: sellers refuse to give up their 3% mortgages.
What It Means for Homebuilder Shares
Rising Treasury yields and mortgage rates near 7% are pressuring homebuilder stocks despite analysts citing strong structural housing demand of roughly five million units. The demand story is real. The near-term earnings story is more complicated.
D.R. Horton closed around $153 on November 6, 2026, and in fiscal year 2026 the company’s revenue fell about 3% to roughly $33.0 billion, with net income down 19%. Management cited weaker demand and lower margins, while continuing to use incentives, smaller homes, and disciplined land spending to address affordability pressure. Gross margin in the fiscal fourth quarter was 19.5%, and the company has said incentives are likely to remain elevated in fiscal 2027.
Lennar and PulteGroup face the same dynamics. Lennar traded around $88.74 and PulteGroup near $132.49 as of the November 6, 2026 close.
Building a Position vs. Waiting It Out
Homebuilder stocks remain a strong long-term buy given the inventory deficit, but short-term performance depends heavily on whether the 10-year Treasury yield stays below its 4.70% danger zone. That yield is already near 4.86%. That matters.
The case for patient accumulation in D.R. Horton or PulteGroup rests on the structural deficit of homes in the United States, not on the rate cycle turning friendly in the next 90 days. Investors adding here should do so in tranches, keeping position sizes small enough to average down if the December hike sends mortgage rates toward 7.5%. Forecasters currently expect the 30-year fixed to stay above 7% throughout 2027. That is the horizon to plan around.
The buyers who lock a rate today and hold the home five years or more will likely look back on 7.18% as manageable. The investors who expect a quick rebound in homebuilder margins may be waiting longer than the consensus currently prices in.