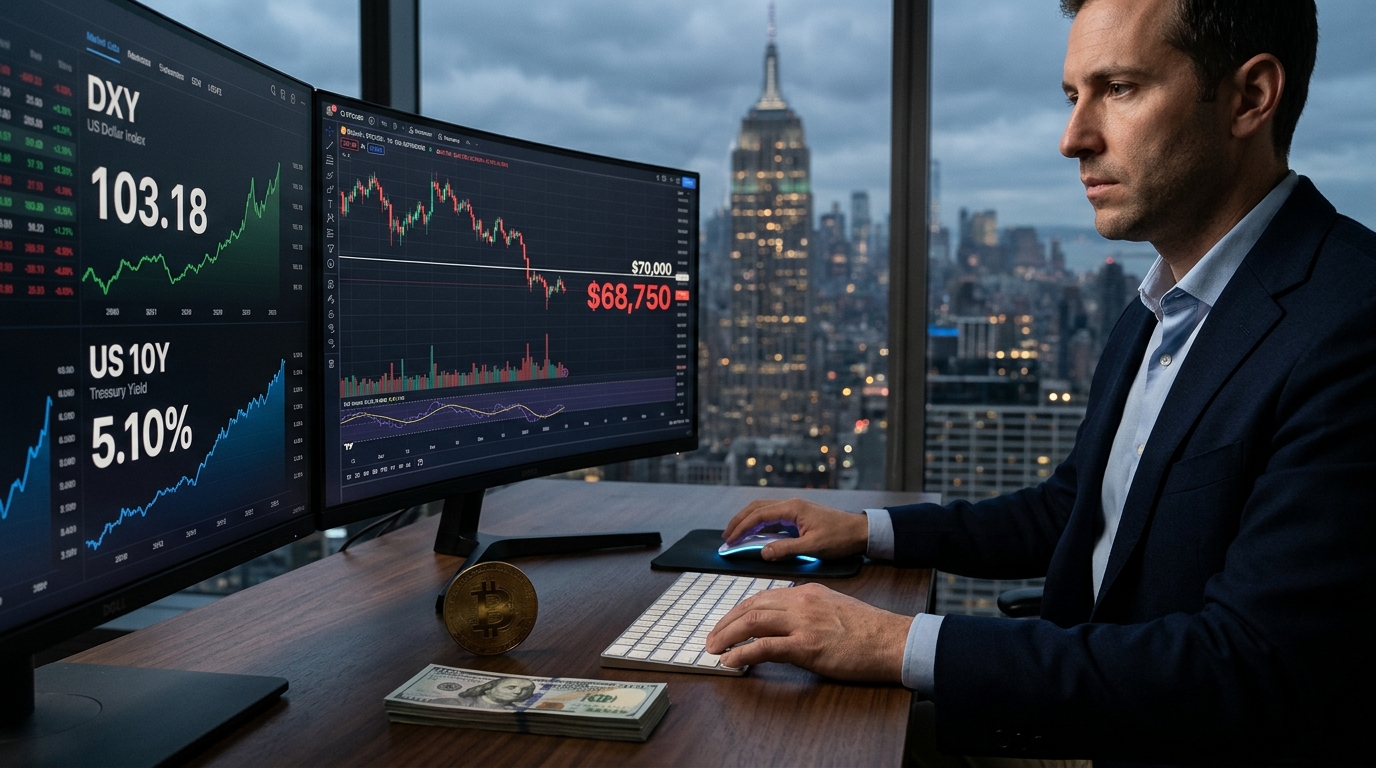
Bitcoin opened Friday at $71,372 and dropped to a session low around $68,052 before stabilizing near $68,400 to $69,000 by mid-morning. That is a roughly 7% decline over 24 hours and places the coin at its weakest level since August. The proximate cause is not on-chain.
The U.S. dollar index traded near 103.18 Friday morning, its highest reading since April 2025, on course for its best weekly gain in two months. The 10-year Treasury yield, which surged more than 13 basis points to about 5.12% on Thursday after bond markets reopened following the Veterans Day holiday, was hovering near 5.10% to 5.12% by Friday morning. Those are not Bitcoin numbers. They are the numbers that reset the discount rate for every risk asset simultaneously, and crypto is not exempt.
The inflation picture accelerated the reset. Tuesday’s hotter-than-expected consumer price index reading pushed traders to treat a December Fed rate hike as the base case, and some forecasters have begun to pencil in additional tightening into early 2027. When the risk-free rate is rising and the dollar is at a 19-month peak, every asset that depends on excess liquidity faces a tighter environment. Bitcoin simply made the move visible first and fastest.
The liquidation cascade added mechanical force. Roughly $1.2 billion to $1.5 billion in leveraged futures were wiped out over 24 hours, with long positions accounting for about 88% to 91% of the total in widely cited tallies. A roughly $31.1 million Bitcoin long on Hyperliquid was among the largest single positions cleared. Total crypto market capitalization fell about 7% to around $2.35 trillion. Ether dropped below $2,000, trading near $1,920.
The institutional channel is draining at the same time. BlackRock’s iShares Bitcoin Trust (IBIT), the dominant spot Bitcoin ETF by assets, has been part of a broader streak of spot Bitcoin ETF outflows in early November, and industry dashboards put the category down about $1.44 billion over five sessions through Wednesday. Whether year-to-date flows have turned negative depends on the data set and cutoff, so treat that claim with caution.
Strategy (MSTR) carries a separate weight. MSCI confirmed on November 11 that it will remove Strategy from the MSCI USA Index, the MSCI World, and the MSCI ACWI after the November 30 close, applying a methodology change that can exclude firms deemed to lack substantial operating assets. JPMorgan has estimated the deletion could force roughly $2.8 billion in passive selling, with an additional $8.8 billion at risk if other index providers follow. Strategy holds approximately 850,364 BTC and has warned in its filings that index exclusions can impair its share price, liquidity, and future capital-raising capacity, the same equity-issuance machine that has funded most of its Bitcoin accumulation.
The stronger case against this read: much of the leveraged overhang may now be cleared, and Bitfinex noted this week that after prior ETF outflow runs in 2026, Bitcoin gained a median 6.4% over the following 10 sessions once net inflows returned for at least three consecutive days. The November 30 passive selling from MSCI rebalancing is known, dated, and largely contained to one trading day.
What to watch: October producer price data, due Friday morning, could either reinforce or soften the inflation argument that has driven yields higher all week. The $70,000 level is now resistance rather than support. A sustained return above it would require either a shift in rate expectations or a halt in ETF outflows. Neither is visible yet.