Dear Reader,
A major AI energy announcement coming November 11 could send one small stock soaring.
As power bills spike and voters reject AI data centers… Elon Musk, Sam Altman, and Mark Zuckerberg are all rushing to buy a new tech that can power AI without ever touching the public grid.
Because it stays off grid, it’s “election proof.”
And demand is so intense that it’s now sold out through 2028.
The only companies that can supply this are still flying under the radar.
But that’s about to change as soon as November 11, when one of the biggest makers of this tech publicly announces details… and shows the world what’s going on.
Click here to learn about the stock that could spike after a big announcement on November 11.
Regards,
Joel Litman
Chief Investment Officer, Altimetry
Ford Reports Wednesday. GM’s 7% Drop on a Good Quarter Is the Warning.
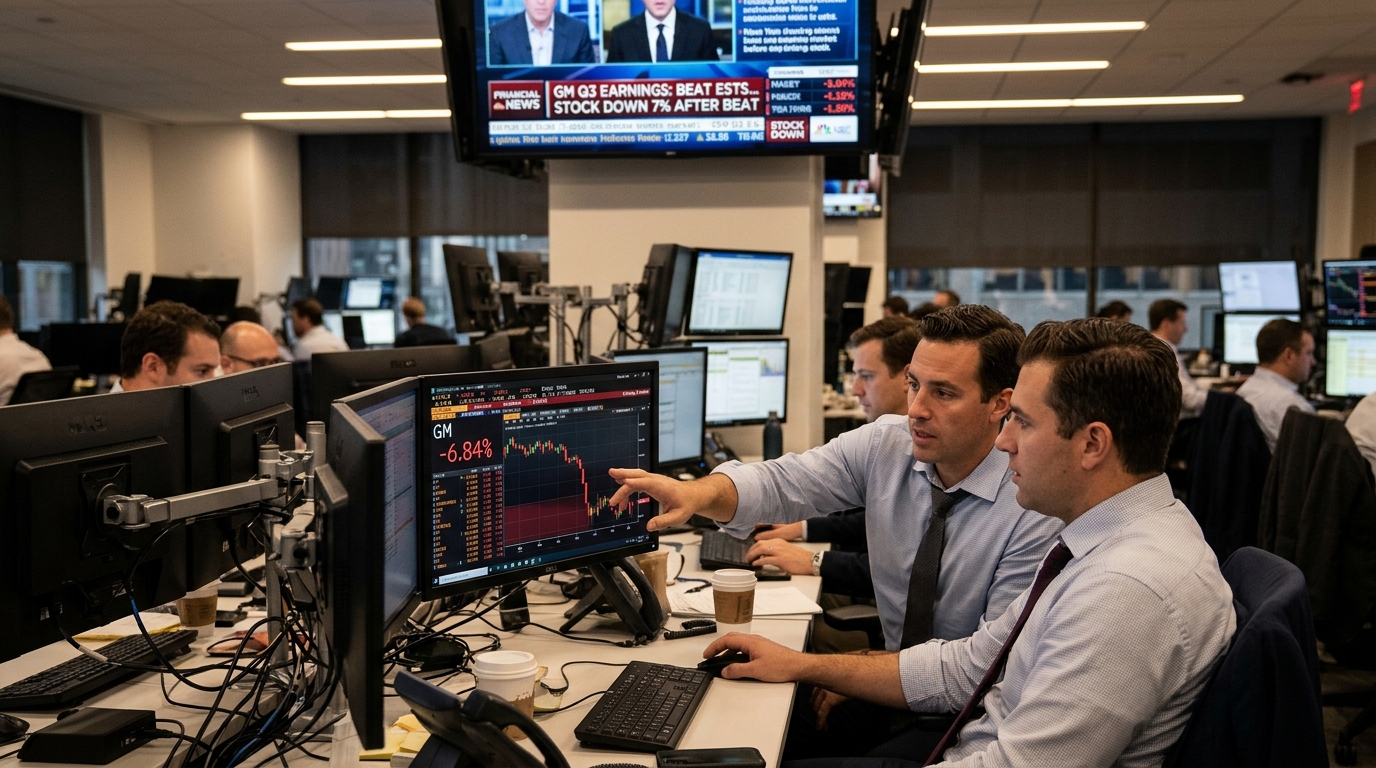
GM delivered one of its cleaner quarters in years on Tuesday, October 20. General Motors beat analyst expectations on both earnings and revenue, reporting adjusted EPS of $3.70. The board authorized a new $20 billion multi-year share repurchase program. The stock fell nearly 7% anyway.
GM fell 6.84% to $77.09 despite the beat. The bigger issue was that investors did not get the kind of forward-step change they wanted, with management updating guidance rather than signaling a clear acceleration. Traders were more focused on management’s caution around costs, as well as the possibility that 2027 growth could be harder to deliver. That is the read-across Ford bulls need to absorb before Wednesday night.
What Ford Has to Defend
Ford’s full-year 2026 adjusted EBIT guidance stands at $10.0 billion to $11.0 billion, with adjusted free cash flow of $6.0 billion to $7.0 billion. On a segment basis, Ford Pro is expected to deliver EBIT of $7.0 billion to $7.5 billion, Ford Blue $5.0 billion to $5.5 billion, and the Model e segment is guiding to a loss of about $4.0 billion.
That $10-11 billion EBIT range was earned under strain. Ford Pro earned $1.7 billion in EBIT in Q2 on $17.8 billion of revenue, with EBIT down year over year as the company worked through the temporary Novelis aluminum disruption. Through mid-year, Ford had incurred about $800 million in Novelis-related temporary costs, with the full-year impact expected at around $1.5 billion. The second half was supposed to be the recovery. Then, in late September, a second disruption arrived.
F-150 production at the end of September was affected by a short-term supplier issue unrelated to aluminum; the expected financial impact is described as containable within the full-year 2026 adjusted EBIT guidance of $10.0 billion to $11.0 billion. Ford management labeled it containable. That word, specifically, is worth scrutinizing Wednesday.
What the Options Market Is Signaling
Ford’s at-the-money implied volatility sits at 43% for the November expiration, against 24% realized volatility over the last 30 trading days, a nearly 20-point premium reflecting options pricing more movement than the stock has recently delivered. IV rank stands at 78 and IV percentile at 87, meaning options are priced at elevated levels relative to the past year. The October 30 expiration prices an expected move of roughly $0.74 on a stock trading near $11.58. That is roughly a 6-7% swing baked into short-dated contracts.
The elevated implied volatility in Ford options is not only about one quarter. GM, Ford, and their suppliers face a live two-sided policy trade as Chinese automakers push for US market access.
Ford reports third-quarter results on October 28 with the stock already down 10.36% over the past month, so even a modest beat could shift sentiment quickly. The Q3 normalized EPS consensus sits at $0.40 versus $0.45 in the prior-year period, a 10.3% year-over-year decline, on revenue of $45.81 billion versus $50.53 billion a year earlier.
The Trade Thesis
The asymmetry here favors the downside. GM demonstrated that beating the quarter does not protect the stock when guidance disappoints or fails to impress at the margin. Ford enters with a lower bar on EPS, yes, but also with two separate supplier disruptions in its recent history, a Model e segment burning $4 billion annually, and a second-half recovery thesis that still needs full confirmation Wednesday night.
A bear put spread on F structured around the October 30 or November 20 expiration defines risk precisely and takes advantage of the elevated implied volatility without requiring a collapse. A $11/$10 put spread, for example, costs a defined premium with the entire position exposed only to that debit if Ford’s guidance holds and the stock rebounds. The GM outcome suggests that even a solid quarter can get sold hard if the forward language disappoints.
The Beast Verdict
GM’s 7% decline on a genuine beat is not an anomaly; it is a data point about how the market is treating legacy automakers right now. Investors are not rewarding reported quarters. They are punishing any whiff of forward uncertainty. Ford faces that same dynamic Wednesday night, with a $10-11 billion annual EBIT promise to defend, a supplier problem it called containable, and a stock already down sharply over the past month. The defined-risk downside is the position with the edge. Monitor guidance language on Ford Pro’s second-half recovery and any update on the September F-150 disruption. Those two items, not the headline EPS, will move the stock.