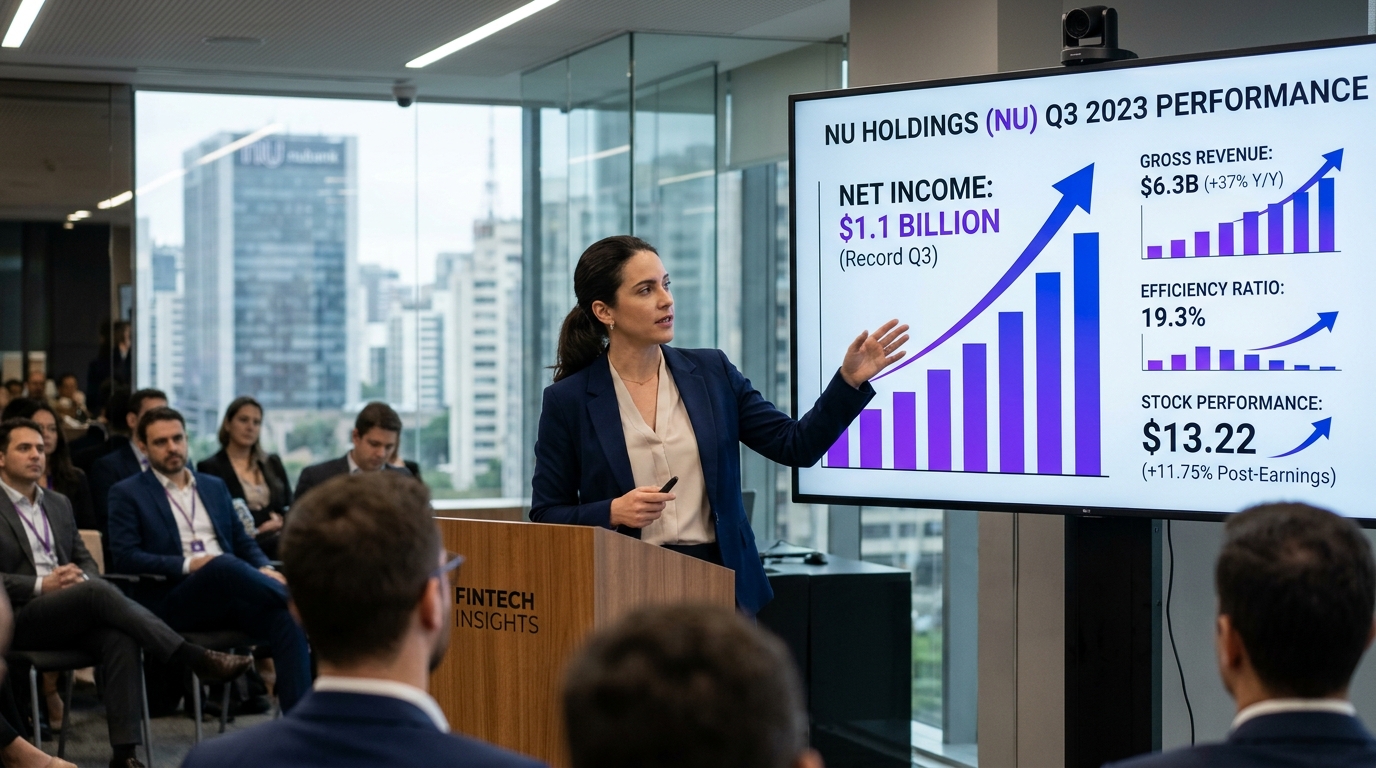
Nu Holdings reported the best quarter in its history on November 12, and the market agreed: shares jumped 11.75% the next day to close at $13.22. That reaction matters, but it is not the reason to buy. The reason to buy is what the numbers say about the business underneath.
Why This Stock Now
Nu reported record gross revenue of $6.3 billion, up 37% year over year, and record net income of $1.1 billion, up 31% on an FX-neutral basis, with a 32% return on equity. At a 32% ROE, Nu is generating returns that most U.S. regional banks would envy. Revenue of $6.26 billion beat the consensus estimate of $5.96 billion by nearly $300 million, a margin of outperformance that is hard to dismiss as noise.
The Business
The company’s customer base expanded from 70 million in Q3 2022 to 143 million in Q3 2026, representing 73 million net additions over four years. That growth has not come at the cost of quality. In Brazil, where Nu already serves 65% of adults, the activity rate rose for the seventh consecutive quarter to a record 86.3%. An 86.3% activity rate at that penetration level is an extraordinary figure. It says the customer base is not dormant; it is deepening.
The efficiency ratio improved to 19.3% versus 20.3% a year ago, with full-year 2026 guidance now set at 19% to 19.5%. For context, most traditional banks in the U.S. run efficiency ratios above 55%. Nu is operating at roughly one-third that cost level, and still investing aggressively.
Why Wall Street Is Paying Attention
Nu US launched on September 10 with a 3.5% APY account, fee-free transfers to Brazil, Mexico, and Colombia, and a no-annual-fee credit card with 1.5% cashback, reaching customers in all 50 states. Nu Global, a stablecoin-based multi-currency account, went live on October 15 and has customers in 37 countries. These are not vaporware announcements. Both products were live before the quarter closed.
In the company’s September 10 announcement, Cristina Junqueira, co-founder and CEO of Nu US, said the company wants to build “the best everyday mobile banking solution.” The ambition is clear: the U.S. consumer banking market dwarfs Latin America in deposit volume.
According to published analyst summaries, the Street’s consensus remains broadly positive on NU, and JPMorgan lifted its price target on NU to $23 while keeping an “overweight” rating.
What’s Driving the Opportunity
The company expanded its credit portfolio to about $41.7 billion while maintaining a return on equity of 32%. Unsecured lending reached $11.3 billion, a year-over-year increase driven by record originations in Brazil. Average revenue per active customer came in at $18, reflecting what management describes as deeper primary banking relationships. The stock, even after Friday’s jump, trades in the mid-to-high teens on trailing earnings based on common data services. That is not an expensive multiple for a company compounding revenue at 37%.
Needham analyst Kyle Peterson noted that both Mexico and Colombia exceeded 15% penetration, with credit and deposit products quickly gaining momentum. Mexico added 870,000 customers in its first quarter as a fully licensed bank. Colombia is now the country’s largest credit card issuer by number of cardholders. The core markets are nowhere near saturation.
What Could Go Wrong
The risks are real and worth naming plainly. NPL ratios ticked higher, with the 90-plus-day ratio rising to 7.3% from 6.9% in Q2. Management also flagged that its tax rate is expected to rise in 2027, which will weigh on net income comparisons. The U.S. launch is early-stage and unprofitable; building a consumer banking brand in America against entrenched competitors requires patience and capital.
Then there is the currency. Nu Holdings stock has stayed in a narrow range over the past few weeks, mirroring the performance of other Brazilian companies. Brazilian real depreciation flows directly into dollar-reported financials, and that dynamic has already pushed NU’s stock down from a 52-week high of $18.98 on January 29, 2026. Any further real weakness resets the math regardless of operating performance.
The Bottom Line
Nu is not a cheap stock in the traditional sense. It is a company with 143 million customers, an efficiency ratio that embarrasses legacy banks, a 32% return on equity, and two brand-new businesses in the United States and 37 countries that have not yet contributed a dollar of profit. The market is pricing in Brazil risk and ignoring the optionality. At $13.22, with Wall Street price targets still clustering well above the current quote and JPMorgan sitting at $23, the asymmetry favors the buyer who can tolerate currency volatility and think past the next two quarters.