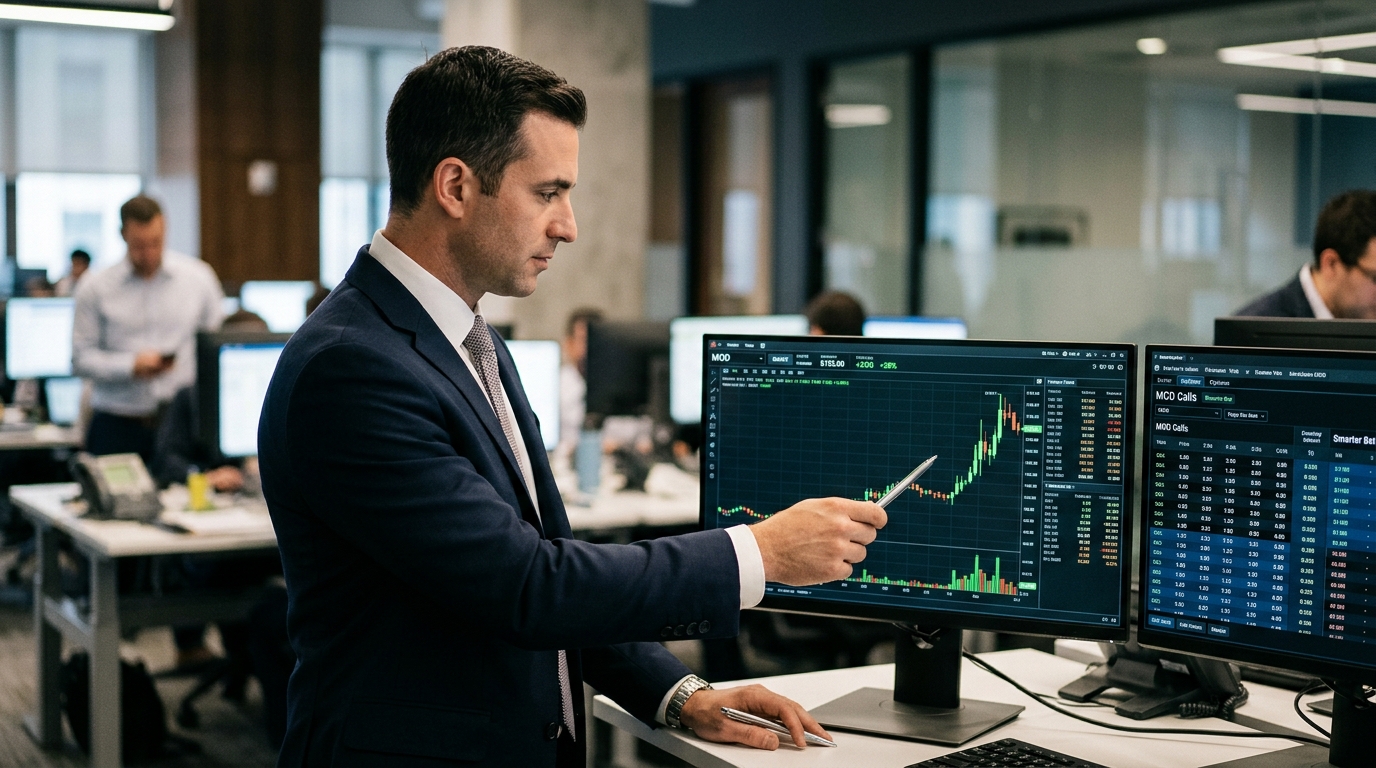
Modine Manufacturing closed Thursday at $106.10 and finished Friday around $135, up nearly 28% on the session. The catalyst: Bloomberg reported that Samsung Electronics is in talks to acquire Modine Manufacturing, a maker of cooling systems for data centers.
A transaction could come together within weeks, though no final decision has been made, the talks could still collapse, and another suitor could yet emerge.
That last clause is where the trade lives.
Why This Trade Stands Out
Chasing MOD shares at a 28% premium to Thursday’s close means paying up for an outcome that is not guaranteed and absorbing full downside if talks collapse. Options reframe that calculus. A defined-risk call position captures the same upside from a competing bid or a confirmed deal announcement at a fraction of the equity exposure. The stock can still correct toward $106 on deal uncertainty; the option holder’s loss is capped at premium paid.
The business underpinning the takeover interest is real and accelerating. In the fourth quarter of fiscal 2026, data center revenues topped $400 million, and for the full year data center sales climbed 73% to more than $1.1 billion, making it the company’s primary growth engine.
Modine also announced a landmark long-term capacity agreement to supply more than $4 billion of data center cooling products between calendar 2027 and 2029, which significantly improves revenue visibility and validates the company’s aggressive capacity expansion plans.
The Story Behind the Trade
Samsung has been assembling a cooling empire. Samsung Electronics completed the acquisition of FläktGroup, Europe’s largest HVAC company, in November 2025.
Modine’s pre-announcement value of about $5.6 billion means a deal would be much larger than the FläktGroup acquisition.
Seoul Economic Daily reported Friday that Samsung is in talks to acquire Modine for $7.5 billion to $8 billion, which, if completed, could surpass the 2017 purchase of Harman to become the largest acquisition in the company’s history.
Samsung is not the only company reshaping its position around AI data center infrastructure through bold acquisitions and partnerships. Marvell Technology’s networking and connectivity chips sit at the same hyperscaler buildout that makes Modine’s cooling capacity strategically valuable.
No price or terms have been confirmed. That gap between rumor and reality is exactly where options earn their keep.
Technical and Fundamental Alignment
Prior to the acquisition talks, Modine shares had been steadily declining since mixed fiscal second-quarter 2027 results. The company missed earnings per share estimates but beat revenue forecasts at $994.4 million. Data center segment sales rose 95% over the prior year, primarily driven by U.S. hyperscale demand. So Friday’s gap ripped a stock that had already pulled back roughly 15% off its early-November close, restoring most of that lost ground in a single session.
The 52-week high was $323.25, hit in late May. Even at $135, MOD sits less than halfway back to that level. If Samsung raises its bid or a second buyer like a large HVAC or semiconductor infrastructure player surfaces, the gap to $200 or beyond reopens quickly.
Options Perspective
MOD’s implied volatility and related percentile metrics moved quickly around the rumor-driven gap. Treat any single-session IV rank and IV percentile read as a snapshot, not a constant, and validate it on your platform before placing the trade.
The preferred structure here is a bull call spread in the January 2027 expiration, targeting the $150/$175 strike range. The long $150 call captures upside from a formal deal announcement or a competing bid. The short $175 call reduces net premium and implicitly sets a profit target consistent with a deal in the $7.5 billion to $8 billion range that Seoul Economic Daily cited. Maximum loss is defined on day one.
Avoid near-term weeklies. M&A timelines are notoriously slippery, and the companies were said to be discussing a potential transaction that could come together within weeks, which still leaves room for a Friday afternoon headline with no deal behind it.
Risk Management
Three things kill this trade. First, talks collapse entirely and MOD retraces toward $106. Second, Samsung agrees to a price already priced into the current stock level, leaving call holders with no incremental move. Third, the broader market sells off sharply, dragging industrial names with it regardless of deal speculation.
Position sizing matters most here. The asymmetry only works if the premium at risk is sized to absorb a total loss without material portfolio damage. Never own more contracts than you are prepared to see expire worthless.
The Beast Verdict
MOD after a 28% gap is not a stock-buying opportunity. It is an options opportunity. The business is legitimate: management expects data center sales growth of 80% to 90% in fiscal 2027. Samsung wants that growth. So might someone else. A January bull call spread on MOD lets you stay in the game at a defined cost while the deal process plays out, rather than buying shares at a price that already assumes success.